Running your own business in Dallas means you’re exposed to liability risks most employees never face. A single lawsuit or accident could wipe out your savings and shut down your operation.
We at Brooks Cannon Insurance Group help independent contractors understand contractor insurance in Dallas so you can protect what you’ve built. The right coverage isn’t optional-it’s the foundation of a sustainable business.
What Liability Risks Actually Threaten Your Dallas Business
Independent contractors in Dallas face liability exposure that most salaried employees never encounter. A client injured at your job site, property damage you cause during a project, or a lawsuit claiming your work caused financial loss can happen faster than you think. The U.S. Small Business Administration reports that small businesses face an average of 1.7 lawsuits per company per year, and many of those stem from liability claims that could have been prevented with proper insurance.
Personal assets are on the line
Without liability coverage, you’re personally responsible for legal fees, settlements, and judgments. This means your personal assets and future income face direct risk from business claims. Texas courts have awarded settlements exceeding $500,000 in cases involving contractor negligence or property damage. Even if you win a lawsuit, legal defense costs can run $10,000 to $50,000 before the case ever reaches trial.
The financial devastation of a single claim
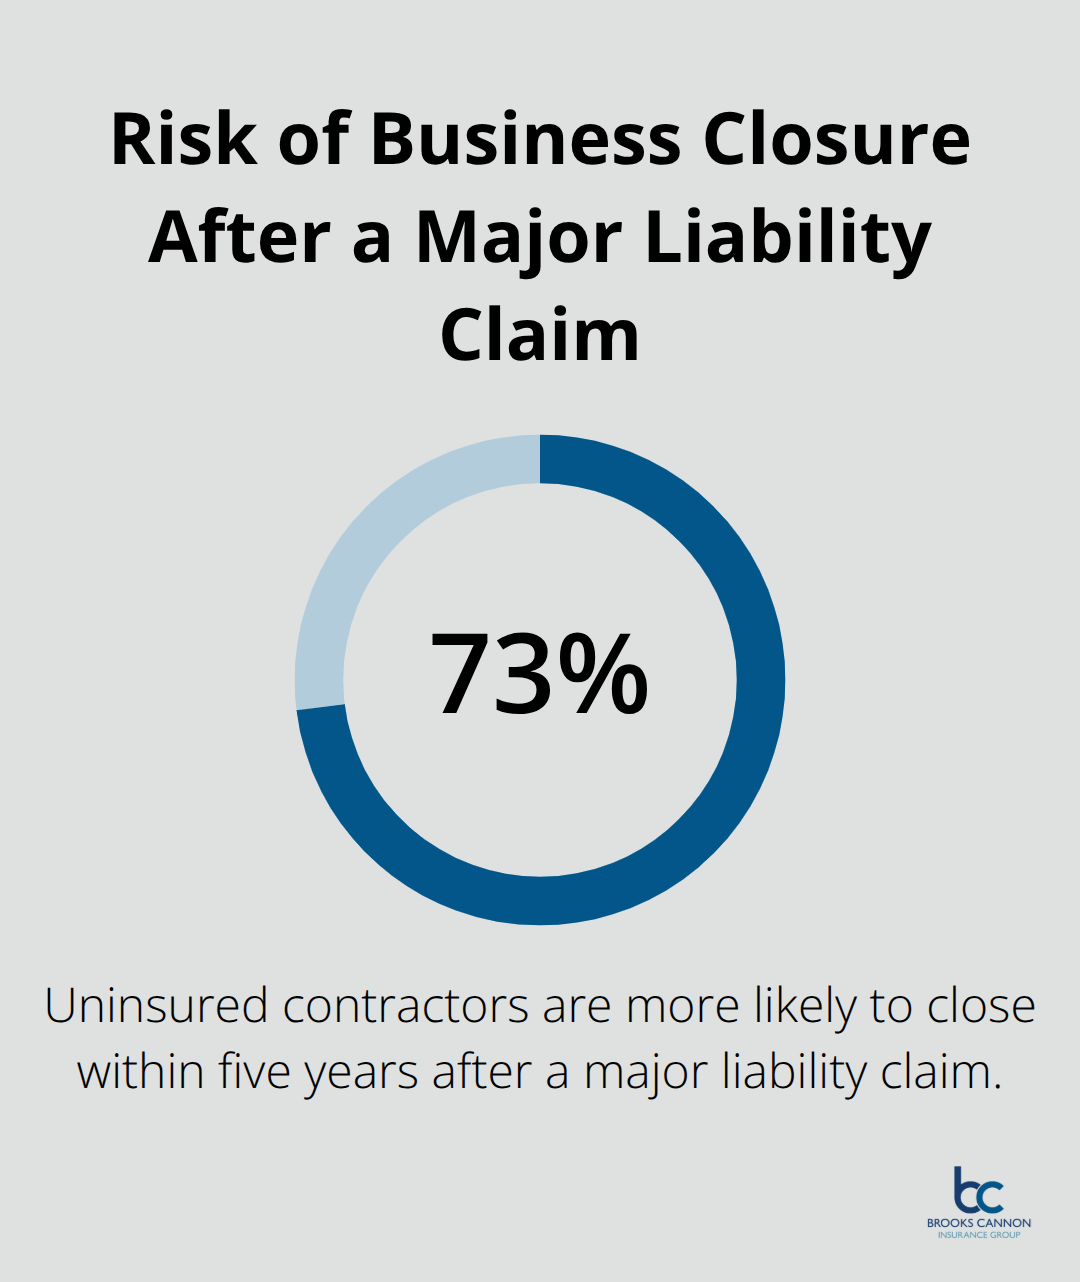
A single liability claim can wipe out your finances. The National Association of Insurance Commissioners found that uninsured contractors are 73% more likely to close their business within five years of a major liability claim. Construction contractors, HVAC technicians, plumbers, and electricians in the Dallas area face particularly high exposure because their work directly impacts client property and safety. One mistake on a residential renovation can trigger claims that exceed your annual income.
Why liability coverage protects your business
General liability insurance protects you when someone claims your work or actions caused them injury or property damage. This coverage pays for medical expenses, legal defense, and settlements up to your policy limits, keeping your personal assets separate from business claims. Dallas contractors operating without this coverage often find themselves unable to bid on jobs requiring insurance proof, which eliminates access to the most profitable contracts. Many commercial clients and property managers won’t hire uninsured contractors at all, cutting off significant revenue opportunities.
The real cost of coverage versus the cost of claims
Liability insurance typically costs between $400 and $1,500 annually for small contractors-a minimal investment compared to the financial devastation of a single uninsured claim. This affordable protection opens doors to better contracts and higher-paying clients who demand proof of coverage. The choice between paying for insurance now or risking everything later becomes clear when you understand what’s at stake.
Understanding these risks sets the stage for selecting the right coverage types for your specific situation.
Coverage Types That Actually Protect Your Dallas Contracting Business
General Liability Forms Your Foundation
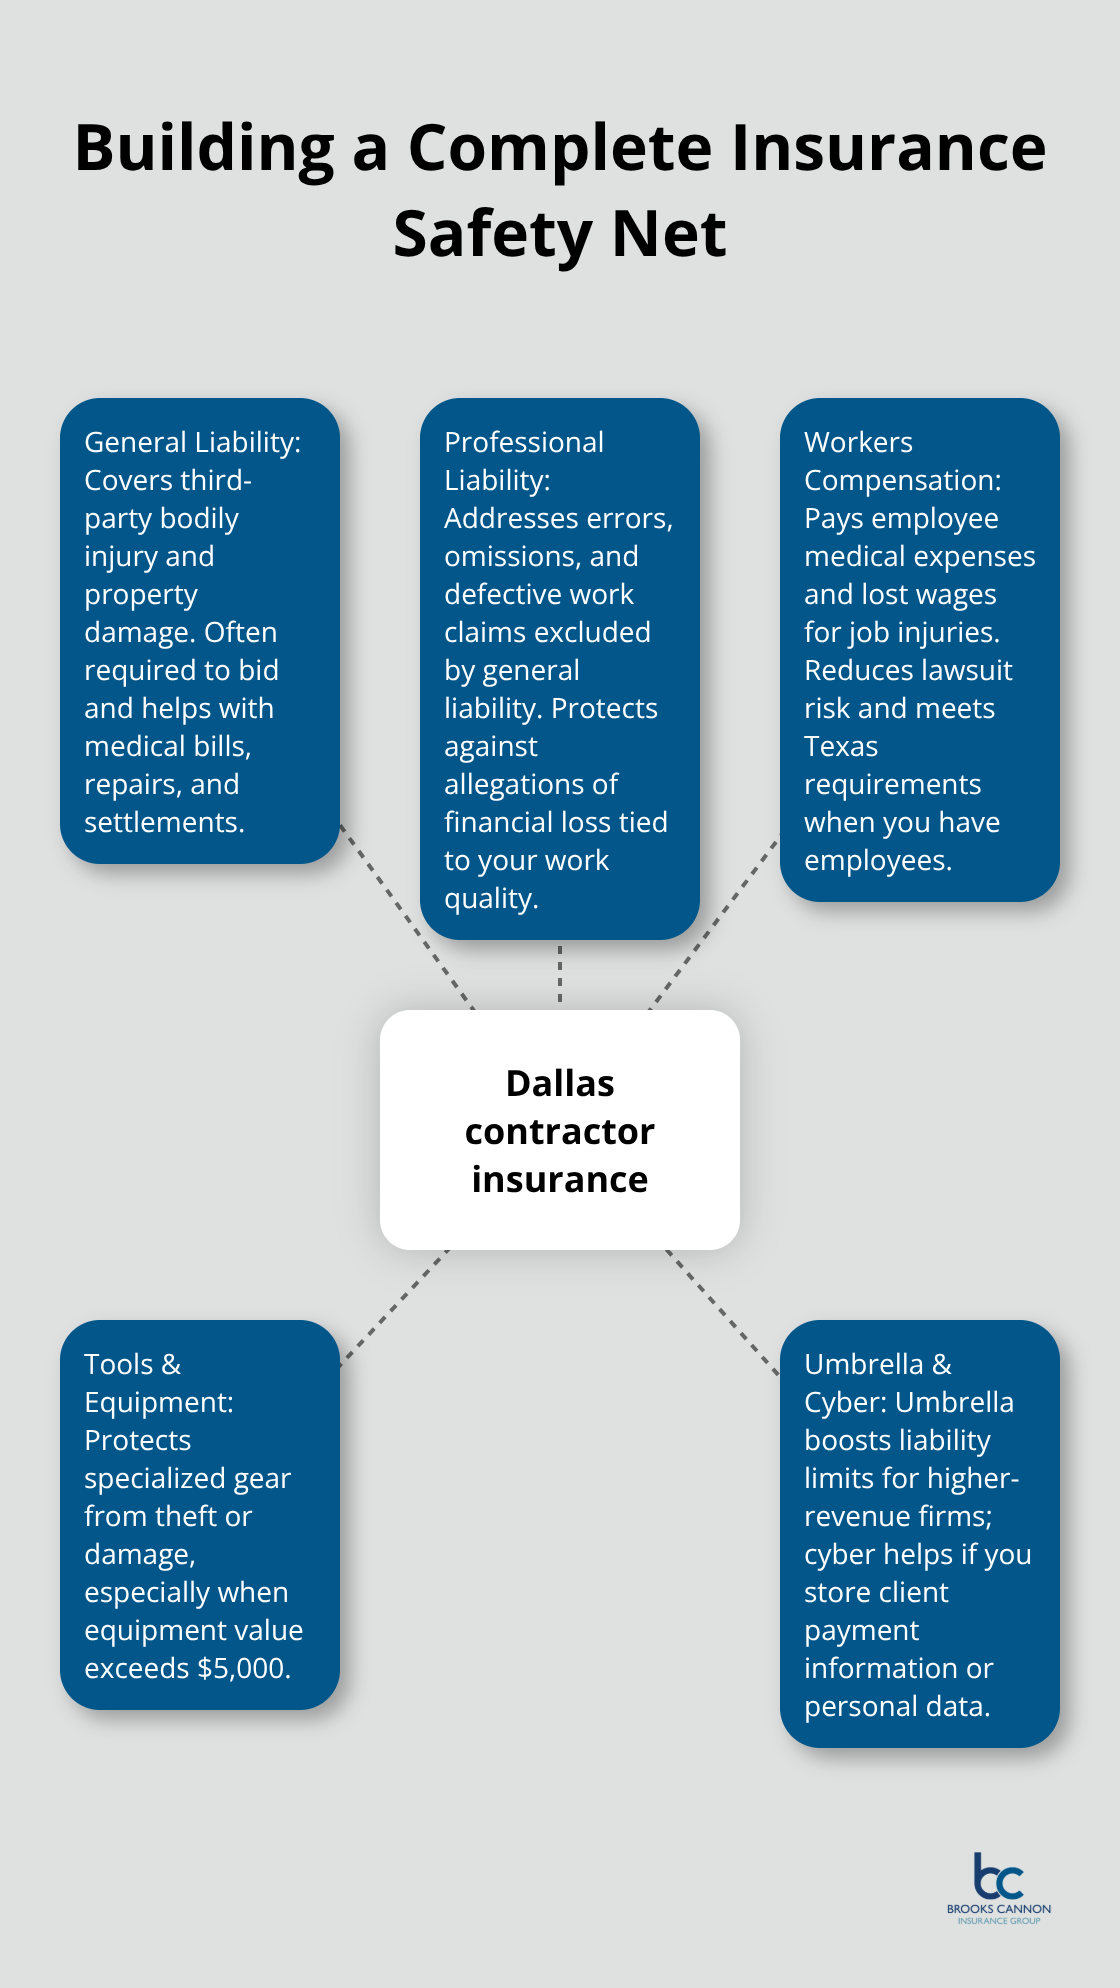
General liability insurance forms the foundation of contractor protection, but it only covers third-party bodily injury and property damage claims. If a client slips on your job site or you accidentally damage their home during work, general liability steps in to cover medical bills and repair costs. However, this coverage stops short of protecting you against claims that your work itself was defective or caused financial loss. The Insurance Information Institute reports that contractors carrying only general liability without additional coverages face gaps that leave them vulnerable to industry-specific risks.
Professional Liability Covers Your Work Quality
HVAC technicians, electricians, and plumbers in Dallas frequently encounter situations where a client claims their work caused equipment failure or energy inefficiency, triggering professional liability claims that general policies explicitly exclude. Professional liability insurance fills this gap by protecting contractors from claims related to professional mistakes, errors, or omissions in their work. A Dallas plumber who installs a system that fails within months faces potential claims for the cost of replacement work, lost business income for the client, and sometimes consequential damages. Professional liability typically costs between $600 and $2,000 annually depending on your trade and revenue, making it an affordable addition that protects against your actual work-related exposure.
Workers Compensation Protects Your Team
Workers compensation stands apart as a legal requirement in Texas if you hire any employees, even part-time workers. This coverage pays for employee medical expenses and lost wages if someone on your team gets injured on the job, and it shields you from employee lawsuits over workplace injuries. Failure to carry workers compensation when required results in significant penalties and potential criminal liability.
Additional Coverage Layers for Specific Risks
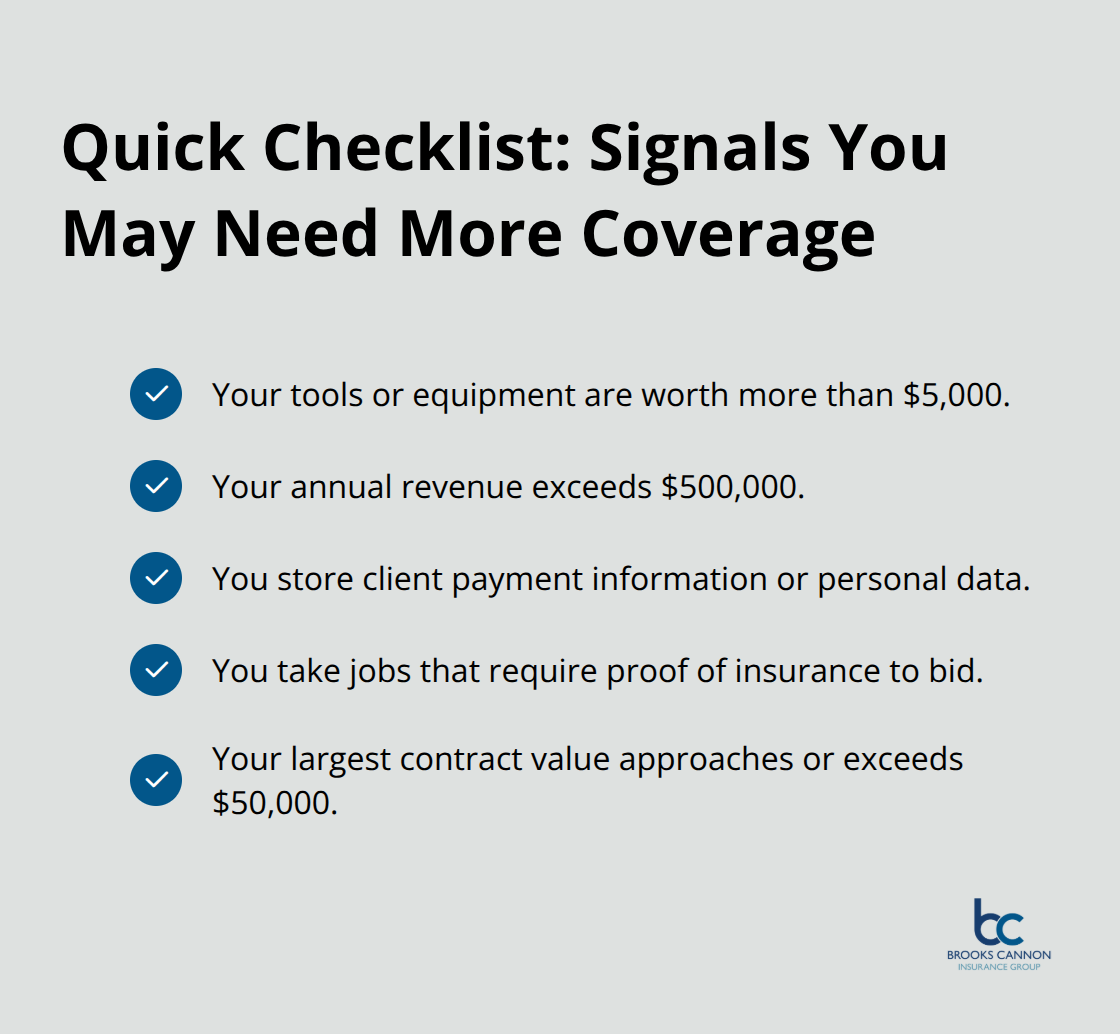
Beyond these core coverages, contractors should evaluate tools and equipment coverage if you own specialized equipment worth more than $5,000, umbrella liability if your annual revenue exceeds $500,000, and cyber liability if you store client payment information or personal data. The combination of general liability, professional liability where applicable, and workers compensation creates a comprehensive safety net that aligns with how Dallas contractors actually operate and where claims actually arise. Selecting the right mix of these coverages depends on your specific industry, revenue level, and the types of risks your daily work creates.
Selecting the Right Coverage Limits for Your Dallas Business
Match Your Coverage Limits to Your Industry Risks
Your industry determines which risks matter most, and those risks directly determine your coverage needs. A plumber in Dallas faces different exposure than an electrician or HVAC technician, which means your liability limits should reflect what actually happens in your work. Start by examining your past projects and identifying where claims have occurred in your trade. Talk to contractors in your specific field about claims they’ve seen or experienced. This matters because it tells you whether a $300,000 general liability limit will actually protect you or leave you exposed.
Assess Your Project Value Against Coverage Gaps
Many Dallas contractors operate with $500,000 limits and find themselves underinsured after a single claim involving property damage to a client’s home or business interruption losses. Your coverage limits should align with your annual revenue and the maximum exposure you could face on a single project. If your largest contract is worth $50,000, carrying only $250,000 in coverage leaves dangerous gaps. Contractors generating $300,000 annually should carry at minimum $500,000 to $1,000,000 in general liability coverage.
Professional liability limits matter equally for service trades. A failed HVAC installation causing equipment damage can trigger claims exceeding $100,000 easily when the client factors in replacement equipment, labor to fix the problem, and business downtime. Setting your professional liability limits below your average project value invites financial disaster.
Choose Deductibles Based on Your Cash Position
Deductibles represent the amount you pay toward claims before insurance activates, and choosing this number requires honest assessment of your cash reserves. A $1,000 deductible costs less monthly than a $500 deductible, but only if you can actually afford to pay $1,000 out of pocket when a claim occurs. Many Dallas contractors operate with thin margins and cannot absorb unexpected $2,500 or $5,000 deductible payments, making lower deductibles the practical choice even if premiums cost slightly more.
Compare Quotes Across Multiple Carriers
Work with an independent agent who represents multiple carriers because rates and deductible options vary dramatically. One carrier might charge $850 annually for $500,000 coverage with a $1,000 deductible while another charges $720 for identical coverage with a $2,500 deductible. These differences compound over years. An independent agent can also identify discounts you qualify for based on safety training, years in business, or bundling multiple policies. We at Brooks Cannon Insurance Group work with multiple top-rated insurance carriers to find the best coverage and pricing for your unique situation, so you see exactly what different coverage combinations cost and what they protect.
Final Thoughts
Liability exposure threatens every Dallas independent contractor, and operating without proper coverage risks your business and personal finances. A single claim can destroy years of work, but contractor insurance Dallas contractors actually need costs far less than most expect. General liability, professional liability for your trade, and workers compensation if you hire employees form the complete protection that keeps your operation running and your personal assets safe.
Three concrete steps move you forward immediately. First, talk to other contractors in your field to identify which risks actually occur in your trade and what claims you should prepare for. Second, set coverage limits that match your annual revenue and your largest project value, not arbitrary numbers that leave dangerous gaps. Third, contact Brooks Cannon Insurance Group to compare quotes across multiple carriers and find the coverage combination that protects your specific risks at competitive rates.
Your business is too valuable to leave unprotected, and one conversation with our team eliminates the guesswork from your decision.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation