Your Dallas business faces liability risks that standard general liability insurance doesn’t cover. A single lawsuit could threaten everything you’ve built, which is why commercial umbrella coverage in Dallas exists.
We at Brooks Cannon Insurance Group help business owners understand when this extra layer of protection becomes necessary. This guide walks you through what umbrella insurance is, who needs it, and how to select the right policy for your situation.
What Commercial Umbrella Insurance Actually Covers
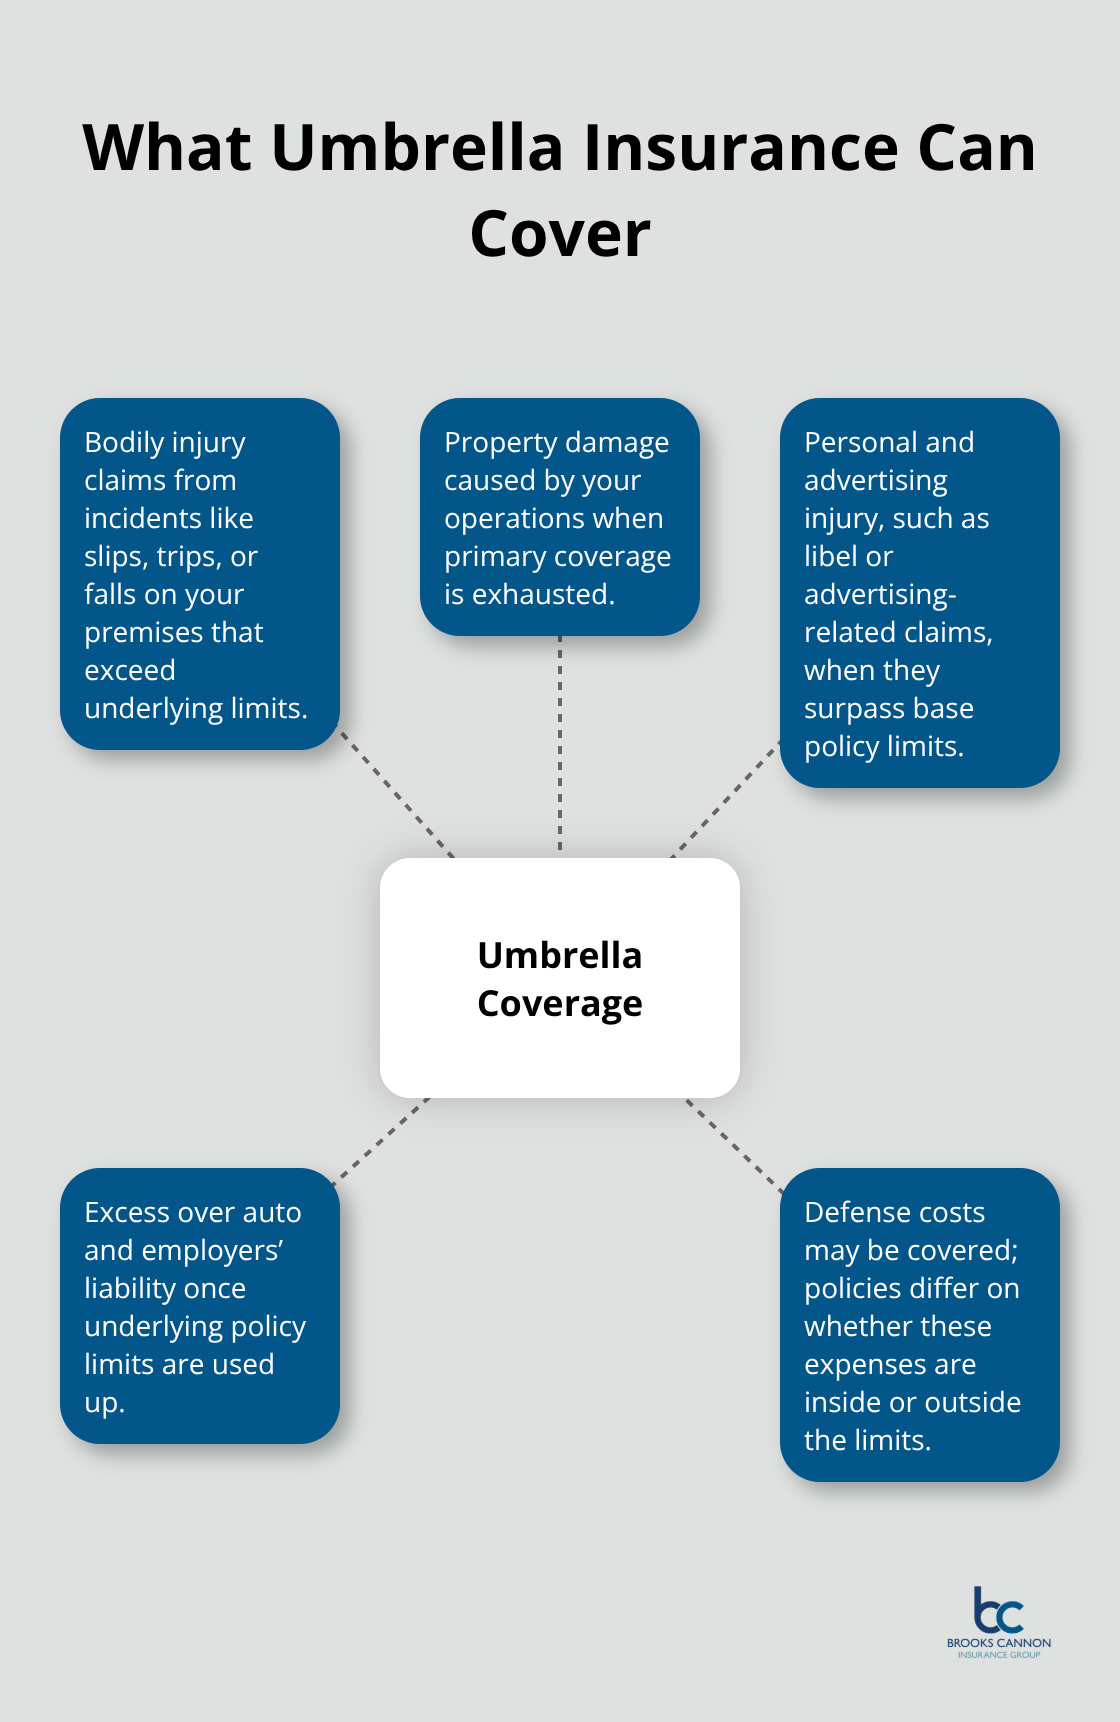
Commercial umbrella insurance sits above your existing liability policies and activates only after those underlying limits are exhausted. According to the Insurance Information Institute, an umbrella policy provides extra coverage beyond your general liability, auto, and employers’ liability policies. Here’s the practical reality: if a major lawsuit hits your Dallas business and the judgment exceeds what your primary policies cover, your personal assets become vulnerable without this protection. The umbrella kicks in at that point, covering the gap between what your underlying policies pay and what you actually owe. This structure matters because you cannot have an umbrella without active underlying policies in place. Most Dallas businesses start with umbrella limits of $1 million and expand to $5 million or more depending on their risk profile and assets. The cost remains surprisingly reasonable relative to the protection it offers; many small business owners find it affordable compared to the catastrophic exposure they carry.
Understanding What Gets Covered
Covered claims typically include bodily injury, property damage, and personal injury claims like advertising injury, according to the Insurance Information Institute. If a customer slips on your Dallas premises and sues for $2.5 million but your general liability only covers $1 million, the umbrella covers the remaining $1.5 million. However, professional liability and errors-and-omissions claims often require separate specialized coverage-the umbrella does not automatically extend to these areas. Defense costs present another important distinction: many umbrella policies cover legal defense expenses, but whether those costs reduce your available limits or sit outside them varies significantly by policy. This detail directly impacts your actual protection, so clarify this with your agent before purchasing.
What Remains Unprotected
The umbrella does not cover indirect losses like business interruption or flood damage; those require separate business owners policies or specialized coverage. Understanding these boundaries prevents costly surprises when claims arise. Your Dallas business may also face specialized risks-cyber liability, product liability, or professional errors-that fall outside standard umbrella protection. These gaps matter because they expose you to significant financial risk even with umbrella coverage in place. Identifying which risks your umbrella actually covers and which ones need separate policies becomes the next critical step in building comprehensive protection for your operation.
Who Actually Needs This Coverage
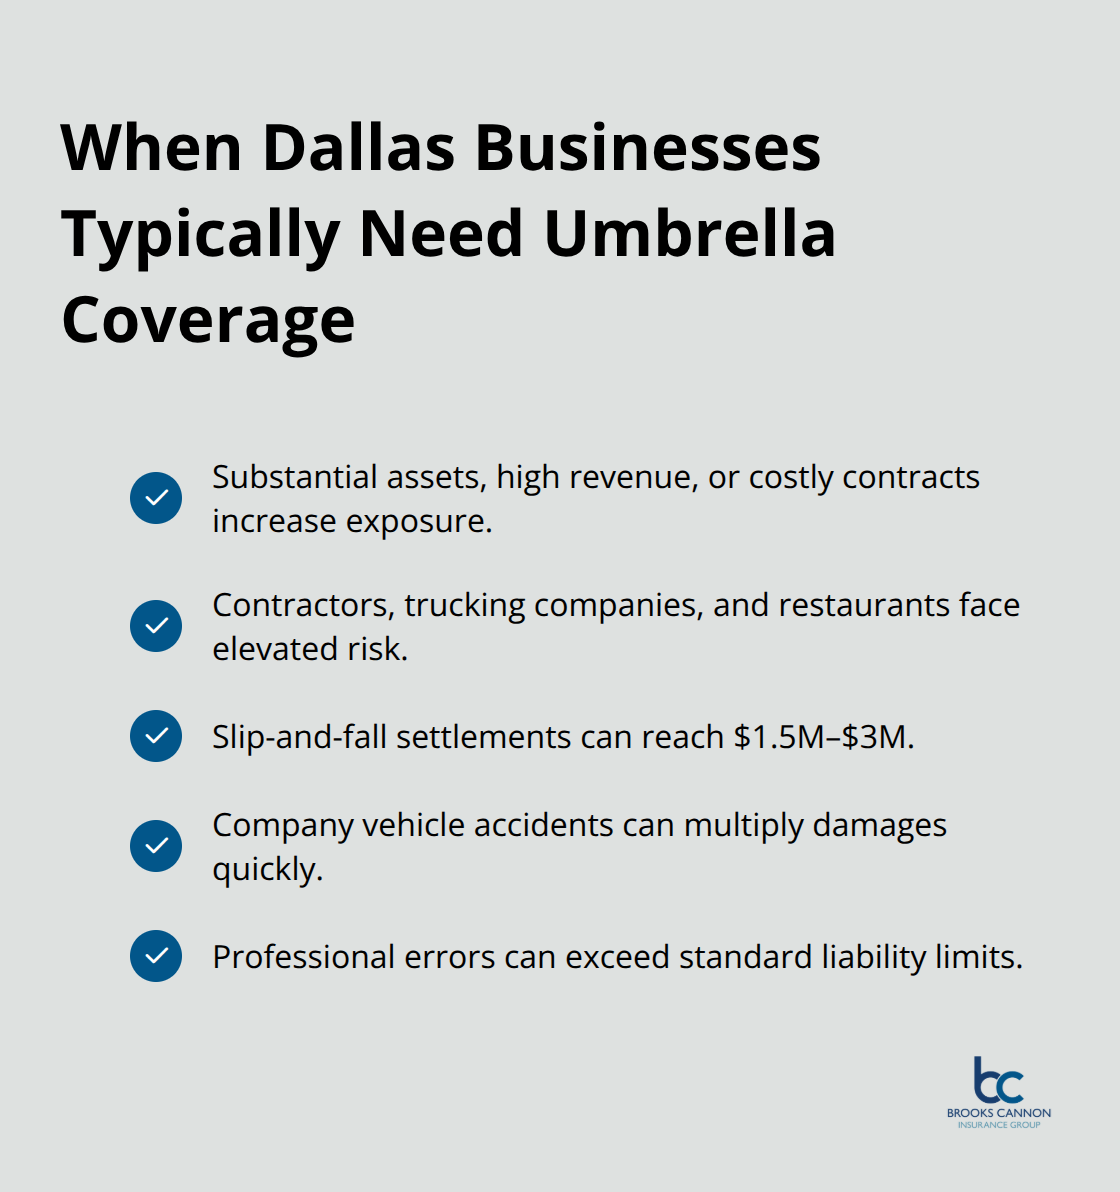
Your Dallas business needs umbrella insurance when your potential liability exposure exceeds what your primary policies cover, and this reality applies far more broadly than most owners realize. The U.S. Small Business Administration notes that Dallas businesses with substantial assets, high revenue, or costly contracts benefit significantly from umbrella coverage to guard against large judgments. Most small to mid-sized Dallas businesses start with $1M to $2M in umbrella coverage, particularly contractors, trucking companies, and restaurants facing elevated exposure. A restaurant with substantial revenue and equipment faces real exposure if a customer suffers a serious injury on premises. A contractor managing multiple job sites across the Dallas area carries exponentially higher risk than a single-location service business. The size of your business matters less than the severity of potential claims and what you personally stand to lose.
When Judgments Exceed Your Primary Limits
If a lawsuit judgment exceeds your underlying general liability limit of $1 million by even $500,000, your personal bank account, home equity, and business assets become targets for collection. This is not theoretical risk-it happens regularly to Dallas business owners who thought their primary coverage was sufficient. Your underlying policies define your actual exposure level, and most Dallas business owners underestimate how quickly claims can exceed those limits.
A slip-and-fall resulting in permanent disability can easily generate settlements between $1.5 million and $3 million depending on the victim’s age and earning capacity. A vehicle accident involving your company fleet where an employee causes serious injuries to multiple people multiplies damages rapidly. Professional service providers face particular exposure because errors in judgment or missed deadlines trigger claims far exceeding standard liability limits.
Where Your Coverage Gaps Appear
If you operate a business where customers, employees, or the public regularly interact with your operations-retail, hospitality, construction, home services-your underlying auto liability and general liability limits become inadequate within months of growth. Defense costs can consume significant portions of your available limits depending on policy language, meaning your actual protection shrinks as legal expenses mount. You should evaluate what a worst-case scenario looks like for your specific Dallas operation and compare that realistic exposure to your current policy limits.
Assets Worth Protecting Drive Coverage Decisions
Your personal financial situation determines how much umbrella coverage you actually need, and this calculation goes beyond just business revenue. If you own your home, have substantial retirement savings, or anticipate future earnings, a judgment creditor can pursue those assets to satisfy a liability claim. Dallas business owners with $500,000 or more in personal net worth face serious jeopardy without umbrella protection.
A judgment of $2 million against your business can result in wage garnishment for years and forced asset liquidation. The question becomes whether you are willing to risk everything you have built to save a few hundred dollars annually on insurance premiums. Contractual requirements with larger clients or government entities in Dallas often mandate minimum liability limits that exceed what your primary policies provide-umbrella coverage helps you meet those requirements without restructuring your entire insurance program.
Scaling Coverage as Your Business Grows
As your business grows and accumulates assets, your umbrella limits should grow with it rather than remaining static at $1 million indefinitely. This means your coverage strategy cannot stay fixed once you purchase an initial policy. The next step involves understanding exactly how much umbrella protection your Dallas operation actually requires and how to select the right policy from available options.
Selecting the Right Coverage Amount for Your Dallas Business
Start your umbrella decision by mapping what you actually own and what a realistic worst-case scenario costs for your operation. Most Dallas business owners guess at coverage needs rather than calculating them, which leaves them either over-insured or dangerously exposed. Take your current general liability limit, your auto liability limit, and your employers’ liability limit, then add them together. That total represents your first layer of protection.
Next, identify what happens if a single claim exceeds that combined amount by a significant margin. A Dallas restaurant owner with $1 million in general liability and $250,000 in auto liability faces $1.25 million in total underlying coverage. If a customer suffers a spinal injury on premises that results in a $3 million settlement, the gap is $1.75 million. That gap is precisely what umbrella insurance fills.
Your Dallas business revenue matters here too. The U.S. Small Business Administration recommends that businesses evaluate potential losses beyond current primary coverage and compare those to their assets and revenue. If your business generates $2 million annually and you personally own $500,000 in assets, a $2 million judgment could force you into bankruptcy. Most Dallas businesses should start with at least $1 million in umbrella coverage, and many should carry $2 million to $5 million depending on their specific exposure.
How to Gather Real Numbers from Your Existing Policies
Pull out your current commercial general liability coverage, auto liability, and employers’ liability policies and write down the exact limits on each one. Do not estimate these numbers. Your insurance agent can provide a summary page that shows all limits clearly.
Next, ask your agent what your actual defense costs situation looks like under each policy. Some policies include defense costs inside the limits, meaning a $1 million limit might only provide $800,000 in actual coverage after legal expenses are paid. Others provide defense costs outside the limits, preserving your full $1 million for actual settlement. This distinction dramatically affects how much umbrella you need.
Then calculate your realistic exposure by considering your business type, number of employees, customer interactions, and contractual obligations. A construction company with 15 employees operating multiple job sites across Dallas carries exponentially higher exposure than a two-person consulting firm. A retail business with 50 daily customer interactions faces different risk than a wholesale operation with minimal public contact.
Comparing Your Assets to Your Potential Liability
Once you have these real numbers, compare them to your personal net worth and business assets. If you own your home, have retirement savings, or anticipate significant future earnings, those assets become targets if a judgment exceeds your coverage. This is the moment to stop thinking about umbrella insurance as an optional add-on and start viewing it as essential protection for what you have built.
Getting Honest Quotes and Understanding Policy Differences
Contact at least three insurance carriers or brokers in the Dallas area to get actual quotes for umbrella coverage at $1 million, $2 million, and $5 million limits. Price alone should not drive your decision, but comparing quotes reveals whether one carrier is pricing you significantly higher than competitors. Most Dallas businesses find that moving from $1 million to $2 million in umbrella coverage costs only an additional $200 to $400 annually, making the upgrade financially sensible for most operations.
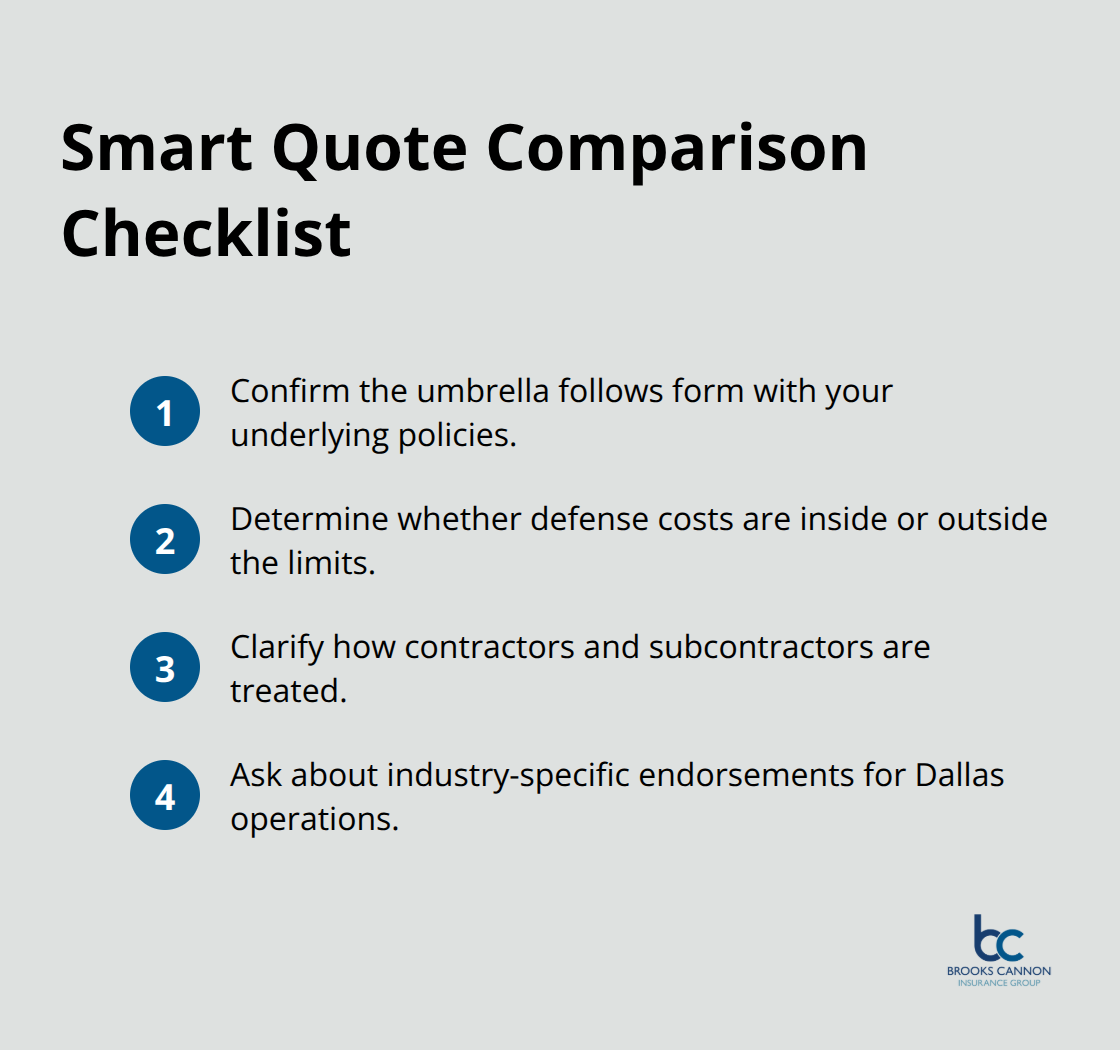
When you receive quotes, ask each carrier the same specific questions about their policy structure. Does their umbrella follow form, meaning it matches your underlying policies exactly, or does it have different definitions and exclusions? Does it cover defense costs inside or outside the limits? What is their stance on contractors and subcontractors if your business uses them regularly? Do they offer any endorsements specific to your industry or Dallas operations?
Carriers differ significantly on these points, and a cheaper quote might provide inferior protection. You must have in-force underlying policies at or above the umbrella limits for the umbrella to respond, so confirm this requirement is met before binding any coverage.
Evaluating Carrier Strength and Local Expertise
Ask whether the carrier offers any premium credits for safety programs, training certifications, or risk management practices your Dallas business already implements. Some carriers provide modest discounts if you bundle umbrella with your underlying policies through the same insurer, though this is not always the best approach financially or from a coverage perspective.
An independent agent familiar with Dallas businesses can compare these nuances more effectively than calling carriers directly, since agents have access to multiple carriers and understand the local market. As an independent agency based in Dallas, Brooks Cannon Insurance Group works with multiple top-rated insurance carriers to find the best coverage and pricing for each client’s unique situation.
Final Thoughts
Commercial umbrella Dallas coverage protects your business and personal assets when liability claims exceed what your primary policies cover. A single lawsuit can cost far more than your underlying coverage limits, and without umbrella protection, you personally absorb the difference. Most Dallas business owners underestimate their exposure until they face an actual claim, at which point protection becomes impossible to obtain.
The practical path forward requires three honest steps. First, gather your current policy limits for general liability, auto liability, and employers’ liability coverage. Second, calculate what a realistic worst-case scenario would cost for your specific operation, then compare that exposure to your personal net worth and business assets (this assessment reveals whether $1 million, $2 million, or $5 million in umbrella coverage makes sense for your situation).
Pricing rarely becomes the limiting factor once you understand your actual need, since moving from $1 million to $2 million in coverage typically costs only a few hundred dollars annually. An independent agent understands how different carriers structure their policies, which endorsements address your specific Dallas industry risks, and how to coordinate umbrella coverage with your underlying policies for maximum protection. Contact Brooks Cannon Insurance Group to discuss your commercial umbrella coverage needs and build a protection strategy that matches your actual exposure.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation