Your Dallas luxury home represents one of your most significant investments. Without a high-value appraisal in Dallas, you risk being underinsured and facing serious financial consequences if disaster strikes.
At Brooks Cannon Insurance Group, we’ve seen too many luxury homeowners discover gaps in their coverage only after filing a claim. The right appraisal protects both your property and your peace of mind.
Why Your Dallas Luxury Home Needs a Precise Appraisal
Standard homeowners insurance policies are built for average properties, not high-end Dallas homes with custom finishes, smart home systems, or architectural features that command premium prices. When you own a luxury property worth $1 million or more, the gap between what your policy covers and what your home is actually worth becomes dangerously wide. Most luxury homeowners carry insufficient coverage because their appraisals fail to reflect the true replacement cost of their properties. If your luxury home suffers a total loss and your appraisal was inaccurate, you’ll face a catastrophic shortfall between your insurance payout and your actual rebuilding costs. Contractors in the Dallas area charge premium rates for custom work, and materials for high-end homes cost significantly more than standard alternatives.
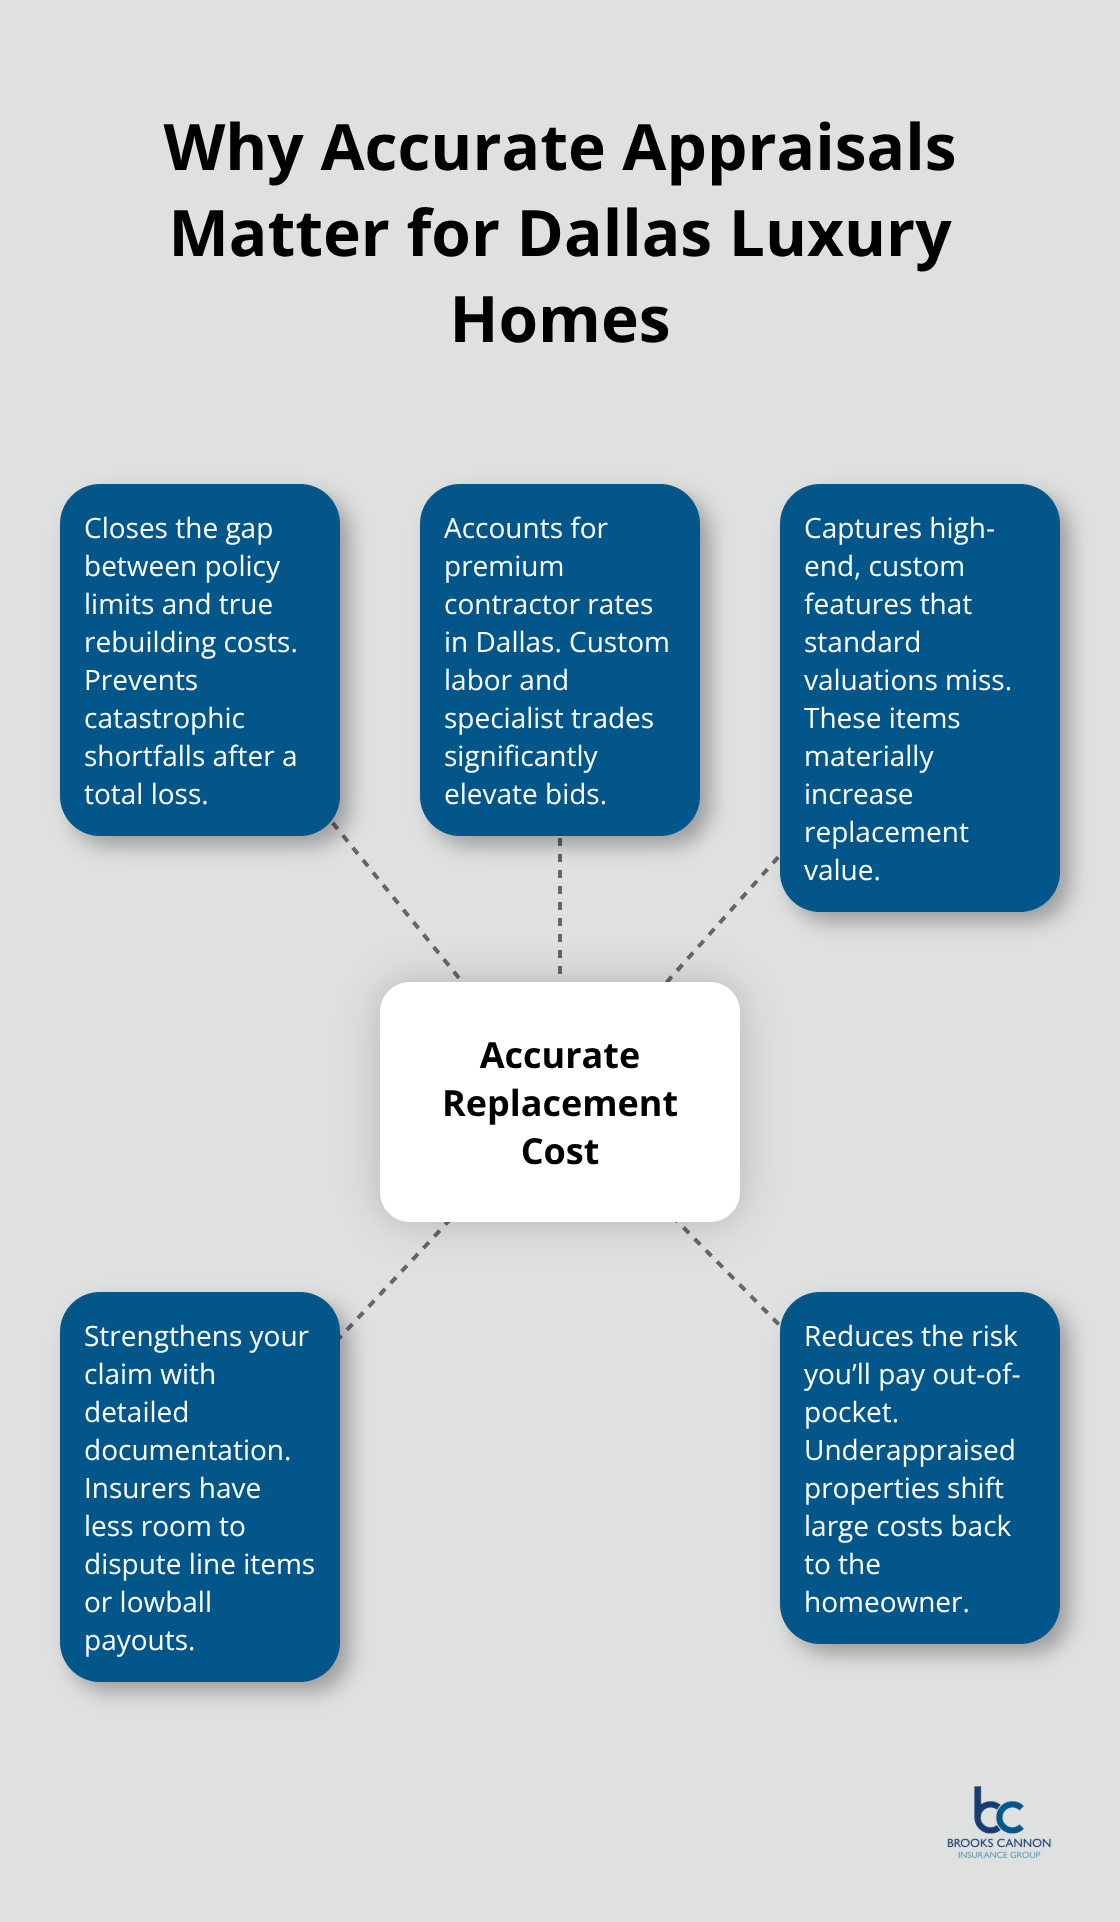
An underappraised property doesn’t just mean a smaller claim payment-it means you absorb the difference personally, potentially losing hundreds of thousands of dollars.
Specialized Appraisals Capture What Standard Valuations Miss
A typical residential appraisal focuses on comparable sales in your neighborhood, but luxury properties rarely have true comparables. Appraisers experienced in high-value homes understand that custom architectural details, imported materials, integrated technology systems, and professional landscaping add value that standard formulas don’t capture. They document smart home automation systems, wine cellars, home theaters, pools with custom finishes, and outdoor kitchens-features that directly impact replacement costs but often get overlooked in generic appraisals. When a claim adjuster reviews your file, they compare your appraisal documentation to the actual damage. If your appraisal is vague or fails to itemize high-end elements, the insurance company will lowball their settlement offer. A detailed appraisal that specifically lists custom features, material specifications, and upgrade costs gives you concrete evidence to support your claim and prevents the insurer from denying coverage based on ambiguity.
Your Appraisal Becomes Your Evidence in a Future Claim
The appraisal you obtain today becomes your evidence in a future claim. If disaster strikes-whether fire, flood, or another covered loss-your insurance company will reference that appraisal to determine what they owe you. An appraiser who understands luxury property valuation will photograph high-end finishes, document custom installations, and create a detailed replacement cost breakdown. This documentation protects your interests. Without it, claim adjusters rely on their own estimates, which are typically conservative and often favor the insurance company’s bottom line. Dallas luxury homeowners should demand appraisals that go beyond market value and specifically address replacement cost, which is what actually matters for insurance purposes. The difference between a $2 million market appraisal and a $2.8 million replacement cost appraisal could mean the difference between recovering fully and facing a six-figure loss.
What Happens When You Work with the Right Appraiser
An appraiser who specializes in luxury properties takes time to understand your home’s unique characteristics. They photograph every custom element, measure high-end finishes, and research the actual cost to replace specific materials and systems. This level of detail matters enormously when you file a claim. Insurance companies scrutinize appraisals closely, and vague documentation gives them room to dispute your claim. A comprehensive appraisal eliminates that ambiguity. The appraiser’s detailed report becomes your strongest defense against underinsurance and claim denials. Finding an appraiser with experience in Dallas luxury homes requires some research, but the investment pays dividends when you need it most.
What Happens During Your Luxury Home Appraisal
A luxury home appraisal in Dallas differs dramatically from a standard residential inspection. The appraiser arrives with specialized knowledge of high-end construction, custom materials, and architectural features that command premium replacement costs. Expect the inspection to take significantly longer than a typical home evaluation-often four to six hours or more for properties over 5,000 square feet with multiple custom systems.
The Appraiser Documents Every Upgraded Element
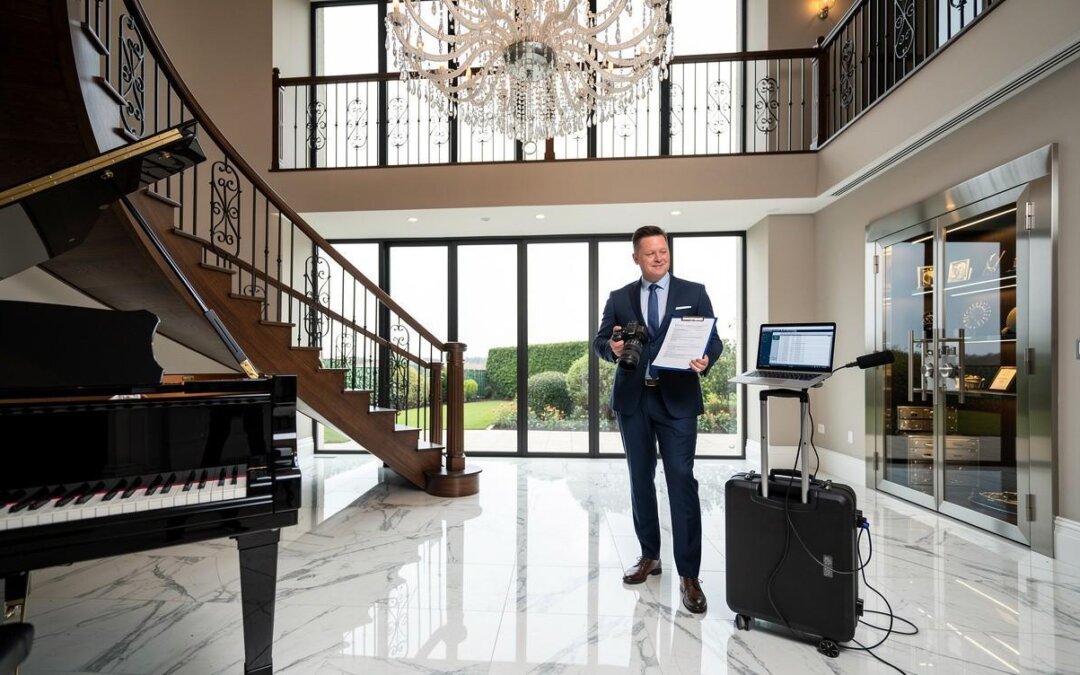
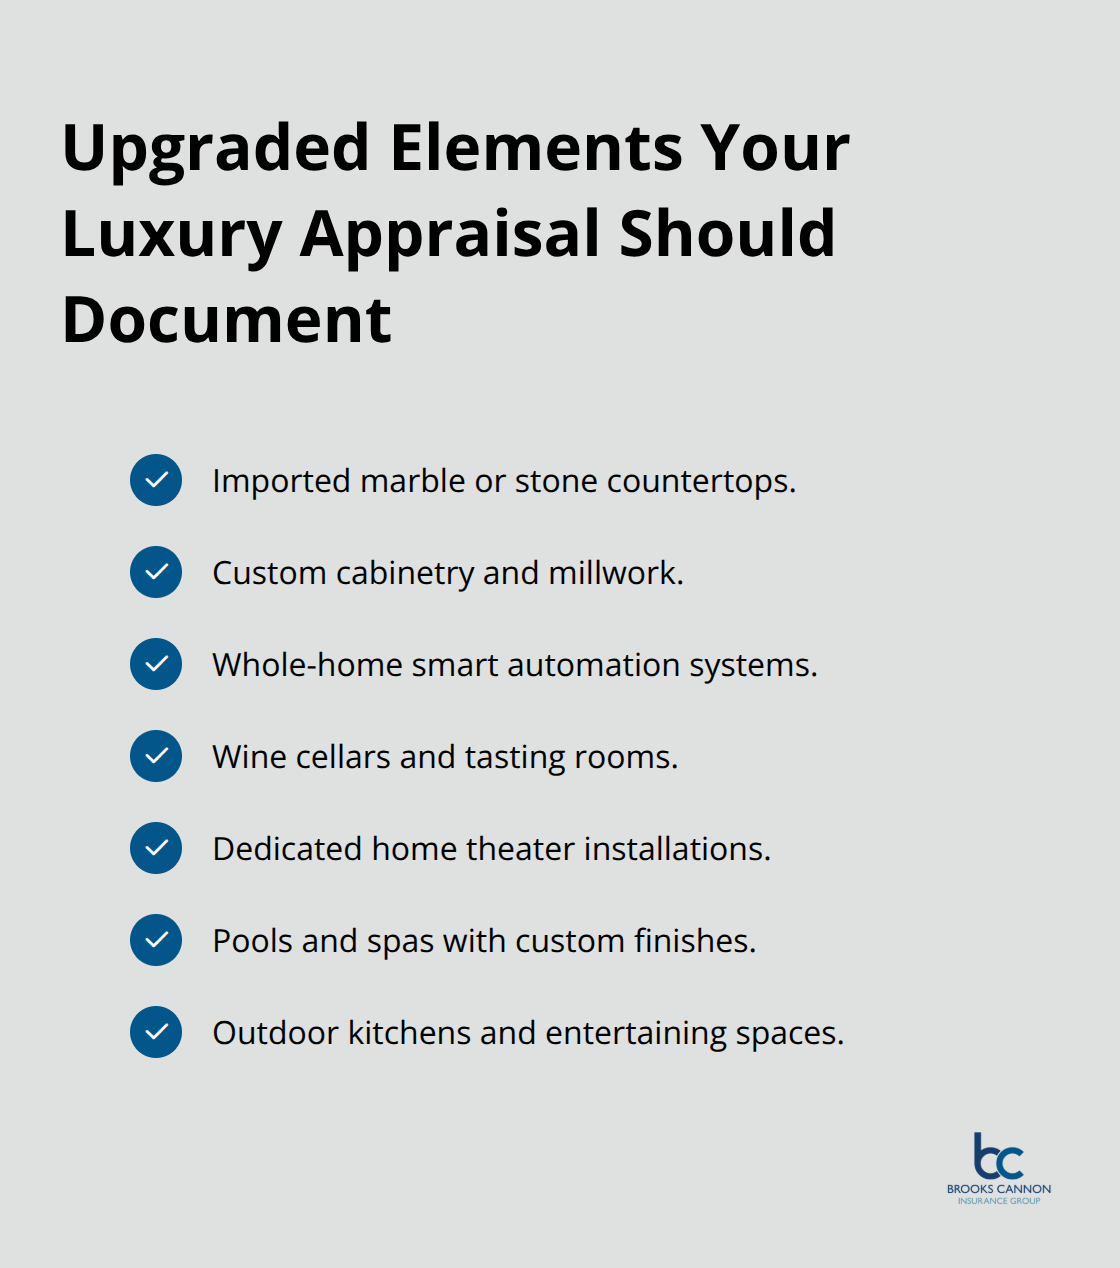
The appraiser photographs every upgraded element: imported marble countertops, custom cabinetry, smart home automation systems, wine cellars, home theaters, pool finishes, and outdoor entertaining spaces. They measure square footage with precision, document the condition of structural elements, and research the actual cost to replace specific materials and systems. Unlike a standard appraisal focused on comparable market sales, a luxury appraisal emphasizes replacement cost documentation. This distinction matters enormously because insurance companies pay based on replacement value, not market value. If your home contains materials sourced internationally or custom architectural elements, the appraiser will note this explicitly and research current pricing for those specific items.
Provide Complete Access to Your Property
Grant the appraiser complete access to all areas of your property, including mechanical rooms, attics, and crawl spaces. They inspect HVAC systems, electrical panels, plumbing installations, and foundation conditions because these factors affect replacement cost estimates. Many Dallas luxury homes feature integrated technology systems-whole-home automation, security infrastructure, and entertainment systems-that require specialized documentation. The appraiser photographs control panels, wiring closets, and system specifications because these upgrades often cost $50,000 to $150,000 or more to replace. Provide receipts or documentation for any major renovations completed in the past five to ten years, as this supports the appraiser’s cost estimates. If you upgraded electrical systems to handle modern demands, installed backup generators, or added solar panels, these improvements need explicit documentation in the appraisal report.
Line-Item Breakdowns Protect Your Interests
The final appraisal report should include a line-item breakdown of replacement costs, not just a single value. A quality report lists specific upgrades with estimated replacement costs: custom kitchen at $85,000, smart home system at $65,000, pool and spa at $120,000, high-end HVAC at $35,000, and so on. This itemization protects you during the claims process because it provides concrete evidence that supports your coverage needs. Insurance companies scrutinize vague appraisals and use ambiguity as justification to reduce claim payments. A comprehensive report with photographs, specifications, and cost breakdowns eliminates that room for dispute. When reviewing the final report, verify that every significant upgrade appears in the documentation and that cost estimates align with current Dallas market rates for luxury construction. If the appraiser’s estimates seem low, request clarification or obtain a second opinion from another luxury property specialist.
Matching Your Coverage to Your Appraisal
The appraisal you approve today becomes the foundation for your insurance coverage limits and your defense against claim denials. Once you receive your detailed appraisal report, the next critical step involves working with an insurance professional who understands how to translate that documentation into appropriate coverage limits. An independent insurance agency can review your appraisal alongside your current policy to identify any gaps between what you own and what your insurance actually covers.
Choosing a Luxury Home Appraiser in Dallas
Start with Qualified Referrals and Credentials
Finding an appraiser who understands luxury property valuation requires more than a quick Google search. Most appraisers in the Dallas area specialize in standard residential properties, which means they lack the expertise to properly evaluate custom finishes, integrated technology systems, and architectural features that define high-end homes. Start by asking your insurance agent for referrals to appraisers with documented experience valuing properties above $1 million. Check the American Society of Appraisers website for members holding the Accredited Member or Senior Appraiser designations, as these credentials require continuing education in property valuation. Verify that any appraiser you consider holds a current Texas license through the Texas Appraiser Licensing and Certification Board.
Prioritize Local Experience with High-Value Properties
Experience matters enormously in this space. An appraiser who has valued fifty luxury Dallas homes understands local construction costs, material pricing, and the specific upgrades that command premium replacement values far better than someone who appraises one luxury property per year. Ask potential appraisers directly how many properties they’ve appraised above $2 million in the past three years and request references from other homeowners or insurance agents they’ve worked with recently. The appraiser’s portfolio of past work reveals whether they possess the specialized knowledge your property demands.
Evaluate Insurance Industry Knowledge
Insurance knowledge separates exceptional appraisers from mediocre ones. A quality appraiser understands that insurance companies require replacement cost documentation, not just market value estimates. They know that claim adjusters scrutinize appraisals for completeness and specificity, and they structure their reports accordingly with detailed line-item breakdowns and photographic evidence. Ask whether the appraiser has experience working with insurance claims or has collaborated with insurance agents on coverage recommendations. Some appraisers simply provide a number without the supporting documentation that protects you during claims.
Obtain Multiple Appraisals for Comparison
Obtain appraisals from at least two different specialists before finalizing your insurance coverage limits. Different appraisers sometimes reach different conclusions about replacement costs based on their assumptions about materials, labor rates, and construction methods. If two appraisals vary by more than 10 percent, request a third opinion to identify which estimate aligns with current Dallas market conditions. This investment in multiple perspectives prevents you from either underinsuring your property or purchasing unnecessary coverage.
Provide Complete Documentation to Support Valuations
Once you’ve selected your appraiser, provide them with documentation of all major renovations, upgrades, and improvements completed within the past decade (including receipts and contractor invoices). This supporting documentation strengthens their cost estimates and gives you concrete evidence during the claims process. The appraiser uses this material to validate their replacement cost calculations and ensure the final report reflects your property’s true value.
Final Thoughts
A high-value appraisal in Dallas protects your luxury home investment in ways that standard insurance policies simply cannot. The detailed documentation, line-item cost breakdowns, and photographic evidence you obtain now become your strongest defense against underinsurance and claim denials when disaster strikes. Without this foundation, you risk losing hundreds of thousands of dollars in potential losses.
The appraisal process requires time and effort, and working with specialists who understand luxury property valuation matters enormously. This investment pays immediate dividends by giving you confidence that your coverage matches your actual replacement costs. We at Brooks Cannon Insurance Group work with Dallas homeowners to translate appraisal documentation into appropriate coverage limits, and our team understands that luxury properties demand specialized attention and that generic policies leave dangerous gaps.
If you’ve obtained a high-value appraisal or are considering one, connect with an insurance professional who can match your coverage to that documentation. Visit Brooks Cannon Insurance Group to schedule a consultation and review your current coverage against your property’s true replacement value.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation