One mistake in your service business can lead to a lawsuit that drains your finances and reputation. At Brooks Cannon Insurance Group, we see Dallas service professionals facing real liability risks every day.
Professional liability in Dallas isn’t just a theoretical concern-it’s a practical threat to your bottom line. The right coverage protects you when clients claim you made errors, caused them financial loss, or failed to deliver promised results.
What Professional Liability Insurance Actually Covers
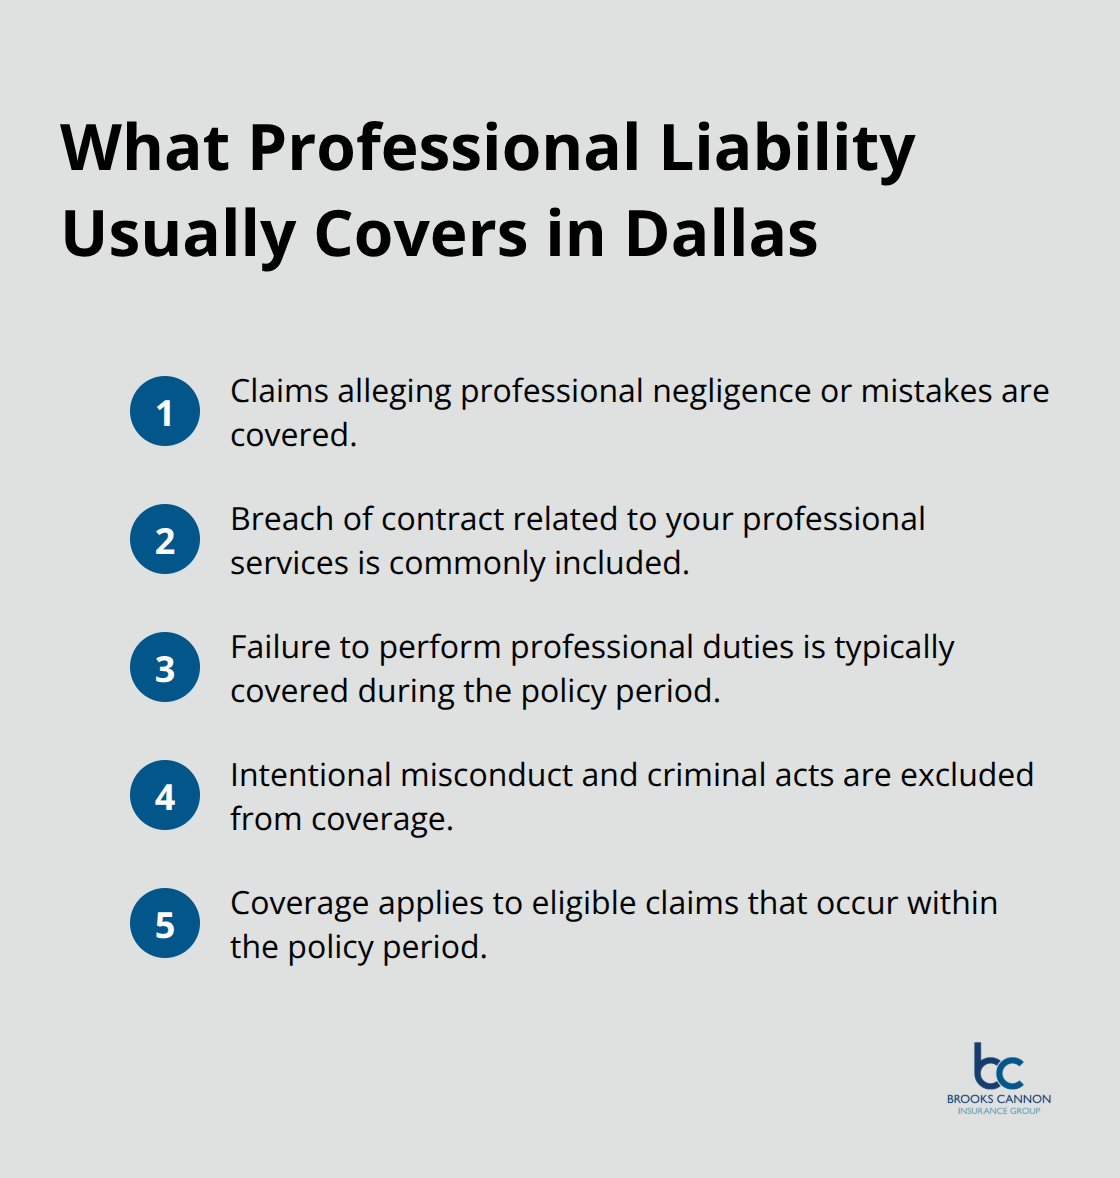
Professional liability insurance protects your Dallas service business from the financial devastation of client claims. When a client alleges you made an error, missed a deadline, or failed to deliver promised results, this coverage pays your legal defense costs and any settlements or judgments against you. Without it, you face personal liability for these expenses, which can easily reach significant amounts in defense costs alone before a case settles. The coverage applies to claims of negligence, breach of contract, or failure to perform professional duties, regardless of whether the claim has merit.
Legal Defense Costs Come First
Insurance companies understand that defending yourself in court costs money before you ever pay out a settlement. Your policy covers attorney fees, court costs, expert witness fees, and investigation expenses from day one. Many Dallas service professionals face claims that are eventually dismissed or won, yet the defense still costs tens of thousands of dollars.
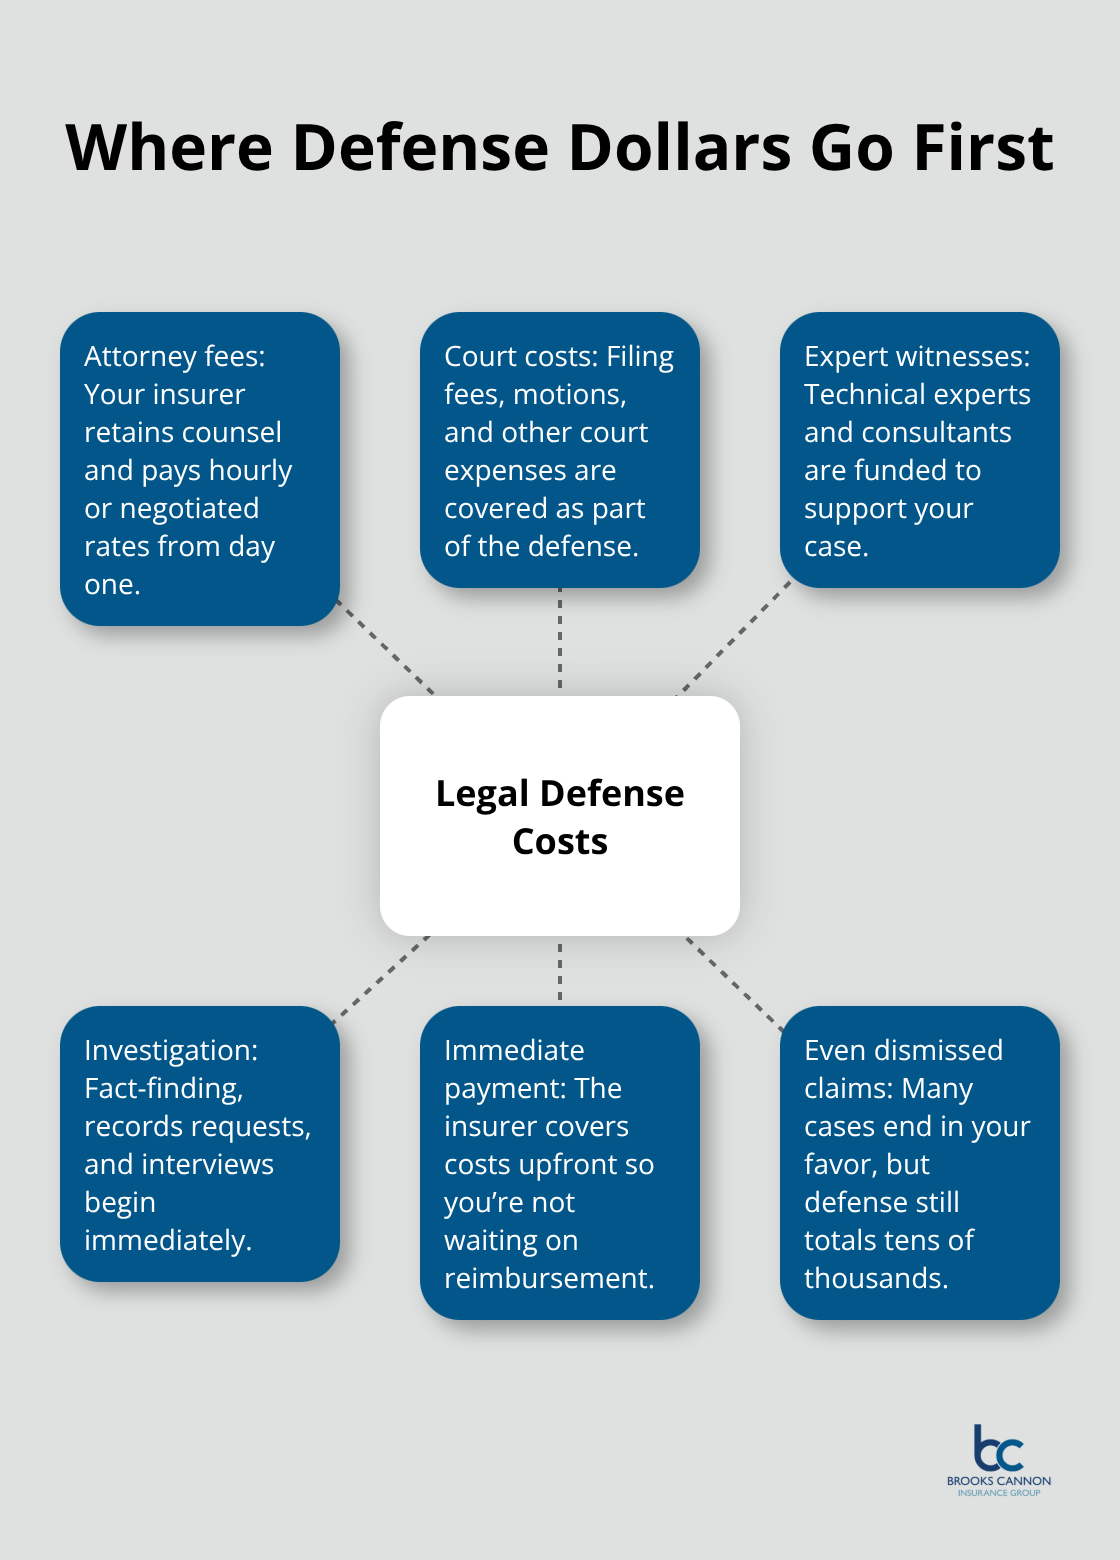
Your insurance company handles these costs immediately, so you don’t pay out of pocket and wait for reimbursement. This distinction separates professional liability from other coverage types and keeps your business operating normally during a dispute.
Settlements and Judgments Are Covered
If a client wins their case or you reach a settlement agreement, your policy pays the award up to your coverage limit. The average professional liability claim costs around $25,000 to $75,000 in total payout, depending on the industry and circumstances. For service businesses in Dallas, a single claim without insurance could wipe out months of profit. Your coverage limit should reflect the maximum financial exposure you face-which is why assessing your specific business risks matters before you purchase a policy.
Negligence and Error Claims Are Standard Coverage
Service businesses face constant exposure to claims that you made mistakes or performed work negligently. A consultant who gave bad advice, a contractor who caused property damage, or a designer who missed project requirements all face these allegations regularly. Professional liability insurance covers these claims as long as they arise from your professional services and occur during your policy period. The coverage excludes intentional misconduct and criminal acts, but honest mistakes and professional errors are exactly what this insurance protects against.
Your specific industry and service type determine which risks matter most for your business. Understanding these vulnerabilities helps you select appropriate coverage limits and identify gaps in your protection.
Why Dallas Service Businesses Face Real Liability Exposure
Client Disputes Happen Constantly in Service Work
Client disputes in service industries aren’t rare exceptions-they’re part of doing business. Dallas contractors, consultants, designers, and service professionals encounter client claims regularly. The Service Trades Council reports that service businesses face claims at significantly higher rates than many other industries, with disputes arising from miscommunication about project scope, timeline delays, or quality concerns. A single unhappy client files a lawsuit claiming you failed to deliver promised results or caused them financial loss, forcing you to hire an attorney immediately. Without professional liability insurance, you pay these legal fees from your business bank account while the claim works through the system-a process that typically takes 12 to 24 months.
Defense Costs Accumulate Faster Than Most Realize
Most Dallas service professionals underestimate how quickly defense costs pile up. Attorney fees in Texas for professional liability claims average around $91 per month for insurance coverage. A roofing contractor facing a water damage claim spends $15,000 to $90,000 just defending themselves before any settlement payment occurs. A business consultant defending against a revenue loss claim faces similar expenses. These costs hit your cash flow immediately, regardless of whether the claim has merit or eventually gets dismissed.
Uninsured Claims Devastate Your Bottom Line
The financial impact of claims without insurance destroys Dallas service businesses of all sizes. A roofing contractor faces a claim that their work caused water damage worth $50,000-without insurance, they’re personally liable for legal defense plus the full settlement amount. A business consultant receives a claim that their advice caused a client to lose $100,000 in revenue-again, personal liability applies. Industry data shows that the average professional liability claim costs between $25,000 and $75,000 in total payout, but uninsured businesses often face additional costs from business interruption and reputational damage.
Insurance Keeps You Competitive in Dallas’s Market
Dallas’s competitive service market means one major claim can force you out of business entirely. Your competitors who carry professional liability coverage continue operating and bidding on projects while you’re fighting a lawsuit. This coverage advantage translates directly to market share and long-term profitability. Service professionals without this protection lose clients, miss opportunities, and watch their business reputation suffer during litigation.
Understanding these vulnerabilities helps you select appropriate coverage limits and identify gaps in your protection-which is exactly what we address when choosing the right professional liability policy for your specific situation.
How to Choose the Right Professional Liability Policy
Match Coverage Limits to Your Actual Business Exposure
Your coverage limit should reflect what a client could actually sue you for, not an arbitrary number you picked from a competitor’s website. A Dallas HVAC contractor faces different maximum exposure than a business consultant, yet both need limits that cover realistic worst-case scenarios. Start by calculating your largest potential project value and the financial loss a client could claim if you failed completely. A roofing contractor installing a $200,000 roof system should carry at least $500,000 in coverage, since water damage claims often exceed the original project cost. A marketing consultant generating $50,000 monthly in client revenue needs higher limits than one generating $10,000 monthly, because the financial loss allegations scale with client impact. Many Dallas service businesses carry $1 million in coverage, which provides solid protection for most situations without excessive premium costs.
Select a Deductible You Can Actually Afford
Your deductible choice matters more than most professionals realize because it directly affects your out-of-pocket exposure on every claim. A $2,500 deductible means you pay the first $2,500 of any claim before insurance kicks in, while a $5,000 deductible saves you premium money but increases your immediate financial responsibility. Try choosing deductibles between $2,500 and $5,000 based on cash flow capacity, not to save a few dollars on premiums. A deductible you cannot actually afford creates a false economy because a claim arrives and you cannot pay your portion, leaving the claim unsettled and your business exposed.
Work with an Independent Agent to Find Competitive Rates
An independent insurance agent who works with multiple carriers finds rates that match your specific risk profile far better than captive agents tied to single companies. We at Brooks Cannon Insurance Group work with top-rated carriers across Texas, which means we can compare pricing for your exact business type rather than forcing you into one company’s rates. A contractor in Dallas with clean claims history might pay $1,200 annually with one carrier and $1,600 with another for identical coverage, a difference that compounds over years. Request quotes from at least two independent agents before purchasing, and ask each agent to explain why their recommended coverage limits and deductibles fit your specific business situation.
Ask the Right Questions Before You Buy
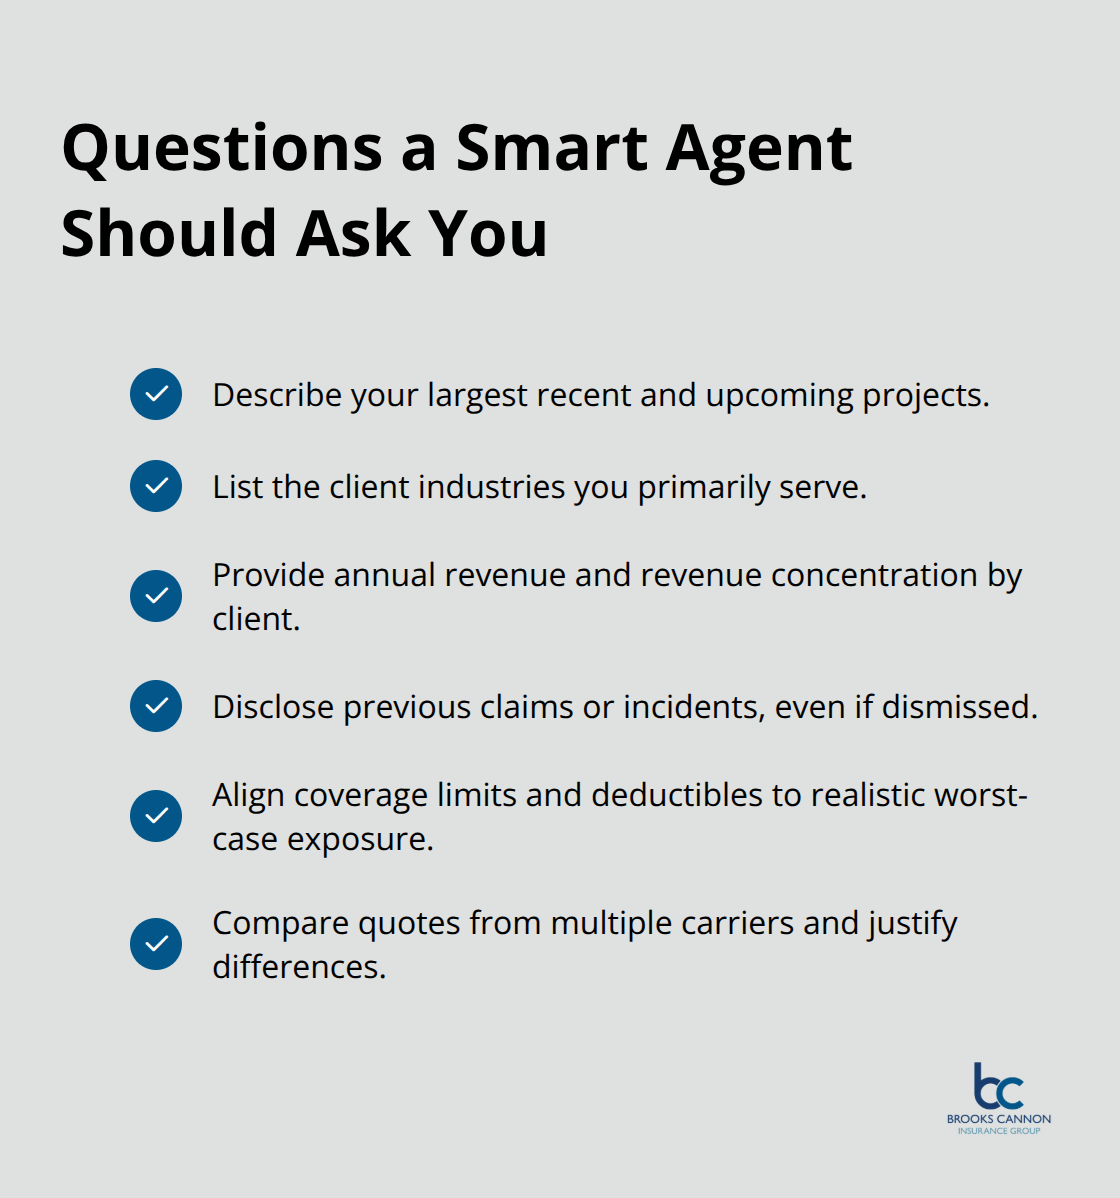
Agents should ask detailed questions about your largest projects, your client industries, your annual revenue, and your previous claims history before recommending coverage limits. If an agent quotes you without understanding these specifics, find a different agent because their recommendations probably won’t protect you adequately. The agent’s willingness to investigate your business thoroughly separates competent representation from generic policy sales.
Final Thoughts
Professional liability insurance protects your Dallas service business from legal defense costs, settlements, and judgments that can wipe out months of profit in weeks. A single claim forces you to choose between paying attorneys or keeping operations running, a choice that destroys most service professionals without coverage. The right professional liability Dallas policy matches your actual project values and client financial impact, not industry averages that miss your specific exposure.
Your deductible should reflect cash you can actually pay when a claim arrives, not a number that sounds good on paper. Working with an independent agent who understands your service type and asks detailed questions about your business exposure separates adequate protection from inadequate coverage. Dallas’s competitive market means your competitors who carry this protection continue bidding on projects while uninsured professionals fight lawsuits and lose clients.
We at Brooks Cannon Insurance Group work with multiple top-rated carriers to find professional liability coverage that fits your specific business situation and budget. Our licensed team asks the right questions about your largest projects, client industries, and revenue to recommend appropriate limits and deductibles. Contact us today to get quotes from carriers that understand Dallas service businesses and price coverage competitively based on your actual risk profile.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation