Your home office is a business asset, but your standard homeowners policy treats it like a spare bedroom. At Brooks Cannon Insurance Group, we see Dallas entrepreneurs lose thousands in claims because their regular coverage doesn’t protect business equipment, client injuries, or inventory.
Home office insurance fills those gaps. The right policy protects both your business and your personal assets when something goes wrong.
What Your Homeowners Policy Won’t Cover for Your Home Office
Business Equipment Sits Outside Your Coverage
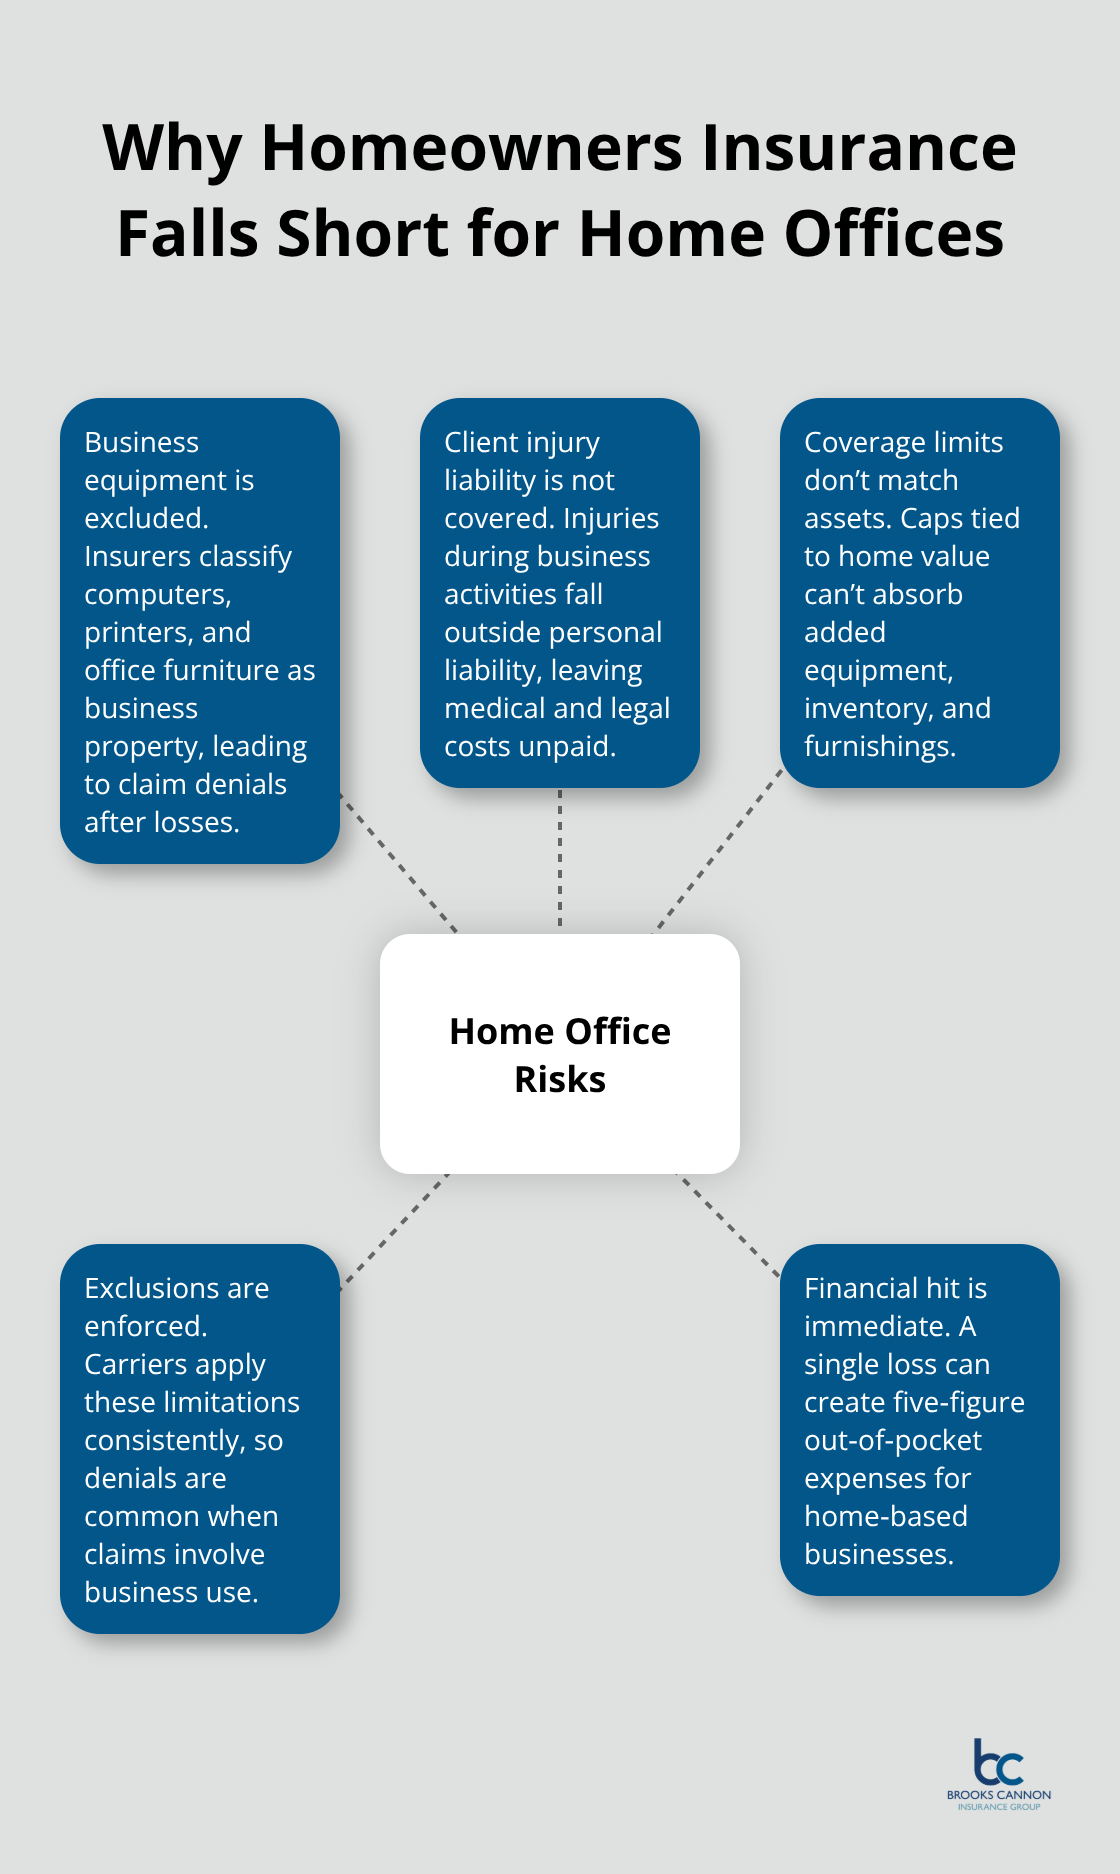
Standard homeowners insurance was built for residential living, not business operations. When you run a business from your Dallas home, your regular policy actively works against you in multiple ways. Business equipment sits outside your coverage entirely. A desktop computer, printer, filing cabinets, and client furniture fall outside protection because insurers classify them as business property rather than personal belongings. If a fire damages your home office setup, you’ll file a claim and receive a denial letter.
Liability Exposure Multiplies When Clients Visit
Liability exposure multiplies when clients, customers, or vendors step into your workspace. Your homeowners policy includes personal liability coverage, but it explicitly excludes injuries or property damage that occur during business activities. If a client trips on your office stairs and breaks their arm, your standard policy won’t pay their medical bills or legal fees. This gap creates serious financial risk for Dallas home business owners.
Coverage Limits Don’t Match Your Business Assets
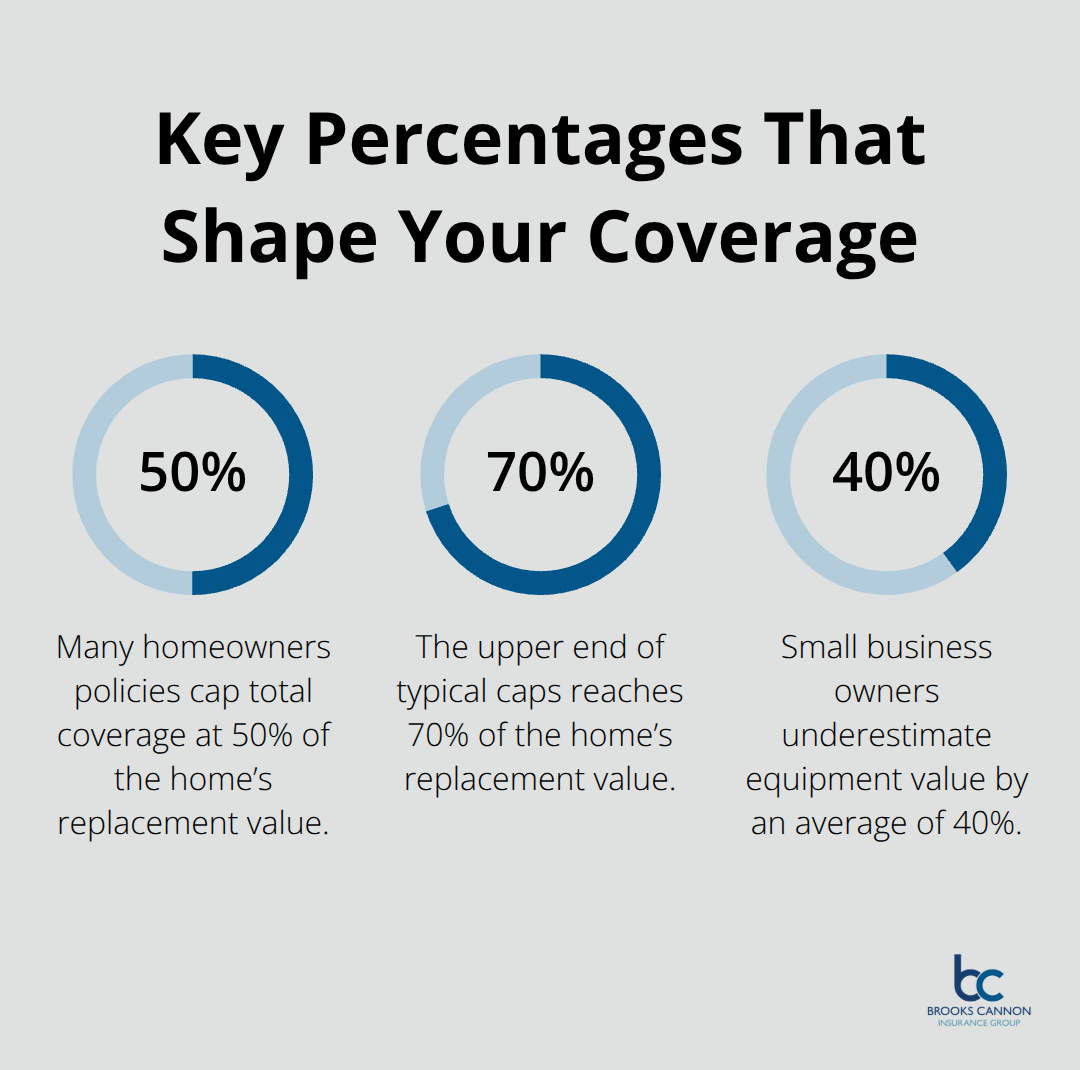
The coverage limits on your homeowners policy assume your possessions fit into a typical household inventory. Most standard policies cap coverage at 50 to 70 percent of your home’s replacement value, which means a $300,000 home typically maxes out around $150,000 to $210,000 total coverage. When you add $40,000 in office equipment, furniture, and inventory to that calculation, you already exceed your policy’s capacity before accounting for anything else in your home.
The Real Cost of These Gaps
The financial consequences of these gaps hit fast. You cannot absorb a $15,000 equipment loss or a $50,000 liability claim from an injured client. Insurance companies maintain these exclusions deliberately and enforce them consistently.
Separate home office coverage addresses these specific gaps. The right policy protects both your business and your personal assets when something goes wrong-and understanding what that coverage actually includes matters more than hoping nothing happens.
What Separate Home Office Coverage Actually Protects
Business Personal Property Coverage Replaces Your Equipment at Full Value
Home office insurance fills the gaps your homeowners policy creates, and the protection works differently than you might expect. Business personal property coverage protects your equipment, furniture, and inventory at replacement cost rather than depreciated value. If your $2,000 laptop gets damaged in a fire, you receive $2,000, not the depreciated $800 your homeowners policy would calculate.
Dallas home business owners typically need between $10,000 and $50,000 in equipment coverage depending on their operation. Most carriers offer this protection through home-based business endorsements that add specific dollar amounts to your existing policy. The National Association of Insurance Commissioners reports that small business owners underestimate their equipment value by an average of 40 percent, which means you likely need more coverage than your initial estimate suggests.
Liability Coverage Protects You When Clients Visit Your Office
Liability coverage in home office policies works the opposite direction from your homeowners liability. Instead of excluding business activities, these policies specifically cover injuries or property damage that occur during business operations. When a client visits your Dallas home office and experiences an accident, your business liability coverage pays their medical expenses, legal costs, and settlements up to your policy limits.
Most carriers offer liability limits ranging from $300,000 to $1,000,000. Given the litigation environment in Texas, Dallas entrepreneurs should carry at least $500,000 in liability protection. This coverage prevents a single accident from wiping out your personal savings and business assets.
Additional Living Expenses Keep Your Business Running During Repairs
Additional living expenses coverage protects you if your home office space becomes unusable due to fire, storm, or other covered damage. This coverage pays for temporary office space rental, equipment replacement costs, and even lost income during the repair period. Unlike homeowners policies that limit these expenses to 20 to 30 percent of your home’s insured value, dedicated business coverage removes those percentage caps and focuses specifically on restoring your business operations.
If your office renovation takes three months and costs $8,000 in temporary workspace, this coverage handles that expense without eating into your personal property limits. Your business continues operating while your home gets repaired, which means your clients and revenue streams stay intact.
Understanding what coverage you actually need requires an honest assessment of your specific business setup and assets. The next section walks through the different policy types available to Dallas home office owners.
Which Policy Structure Fits Your Dallas Home Office
Home-Based Business Endorsements Work for Minimal Operations
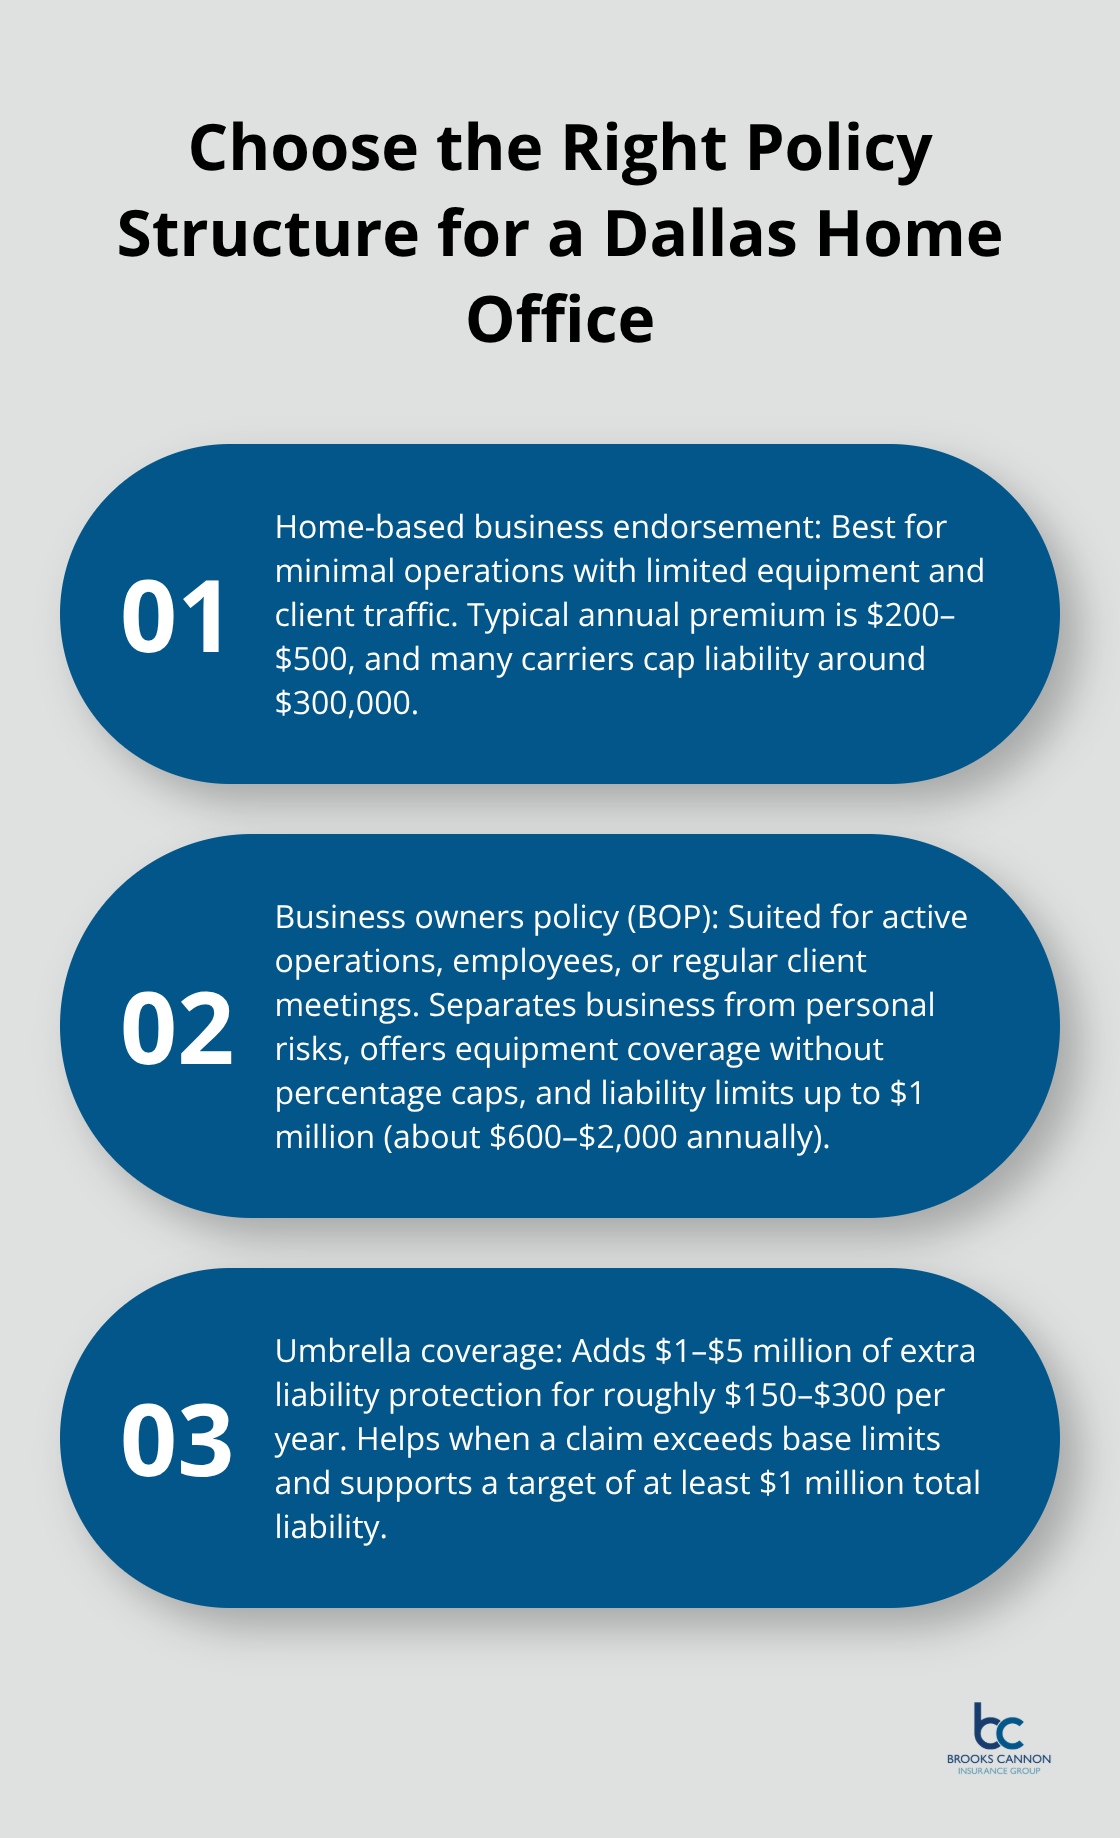
A home-based business endorsement adds coverage to your existing homeowners policy for a modest premium increase, typically between $200 and $500 annually depending on your equipment value and business type. This approach works well if you operate solo, maintain minimal client traffic, and keep equipment under $25,000. The endorsement attaches to your current homeowners policy rather than creating a separate business policy, which means simpler administration and one renewal date. However, endorsements carry strict limitations. Most carriers cap liability coverage at $300,000 and exclude certain business types like consulting practices with frequent client meetings or retail operations. If you run a consulting firm where clients visit weekly, an endorsement leaves you underprotected. If you operate an e-commerce business shipping products from your garage, the endorsement likely won’t cover product liability claims.
Dedicated Business Owners Policies Protect Active Operations
A dedicated business owners policy makes sense if your home office functions like an actual business location. This policy separates your business operations entirely from your personal residence and provides liability limits up to $1 million, equipment coverage without percentage caps, and coverage for business activities that endorsements exclude. Dallas entrepreneurs with dedicated office spaces, employees, or regular client meetings need this structure. The annual cost runs $600 to $2,000 depending on your coverage limits and business classification-a price that seems steep until you consider that a single liability claim without adequate coverage could exceed $100,000. This policy type protects your business assets and personal residence as separate entities, which matters when your home office generates significant revenue or client interaction.
Umbrella Coverage Adds Critical Protection
Umbrella coverage sits on top of either structure and provides an additional $1 million to $5 million in liability protection for roughly $150 to $300 annually. Most Dallas business owners operating from home should carry at least $1 million in total liability protection across their base policy and umbrella combined. This extra layer catches claims that exceed your primary policy limits and prevents a catastrophic lawsuit from destroying your personal finances. Your specific choice depends on whether your home office truly functions as a business location with client visits, employees, or significant inventory, or whether it operates as a quiet workspace where you work solo.
Final Thoughts
Your Dallas home office generates income, but your homeowners policy treats it like a closet. The gaps we’ve outlined-missing equipment coverage, liability exclusions for business activities, and insufficient limits-aren’t theoretical problems. They’re real financial risks that hit when you need protection most. Home office insurance solves this mismatch by protecting both your business assets and your personal residence.
Whether you choose a home-based business endorsement for minimal operations or a dedicated business owners policy for active client interaction, the right coverage matches your actual exposure. Adding umbrella coverage for an extra $150 to $300 annually gives you the liability protection that protects what you’ve built. Solo consultants with occasional client visits need different coverage than e-commerce operators shipping inventory from their garage, and your equipment value, client traffic frequency, and revenue level all determine whether an endorsement suffices or whether you need dedicated business coverage.
At Brooks Cannon Insurance Group, we work with multiple top-rated carriers to find home office insurance that fits your actual business setup and budget. Our licensed experts understand the Dallas home office landscape and know exactly which gaps your current homeowners policy creates. Contact Brooks Cannon Insurance Group to review your current coverage and explore options that protect what you’ve built.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation