Your high-net-worth home deserves protection that matches its value. Most Dallas homeowners with luxury properties don’t realize how many gaps exist in their standard coverage until it’s too late.
At Brooks Cannon Insurance Group, we’ve seen firsthand how exclusions leave expensive homes vulnerable. This guide shows you exactly what your policy doesn’t cover and how to fix it.
What Your High-Value Home Policy Actually Excludes
Standard Exclusions That Leave You Exposed
Most Dallas homeowners with luxury properties assume their standard homeowners policy covers everything inside their walls. It doesn’t. Standard policies typically exclude damage from water backup, sump pump failure, and foundation cracks-three of the most common claims we handle in high-value homes. Your policy also won’t cover losses from earthquakes, sinkholes, or wear and tear, regardless of how expensive your home is.
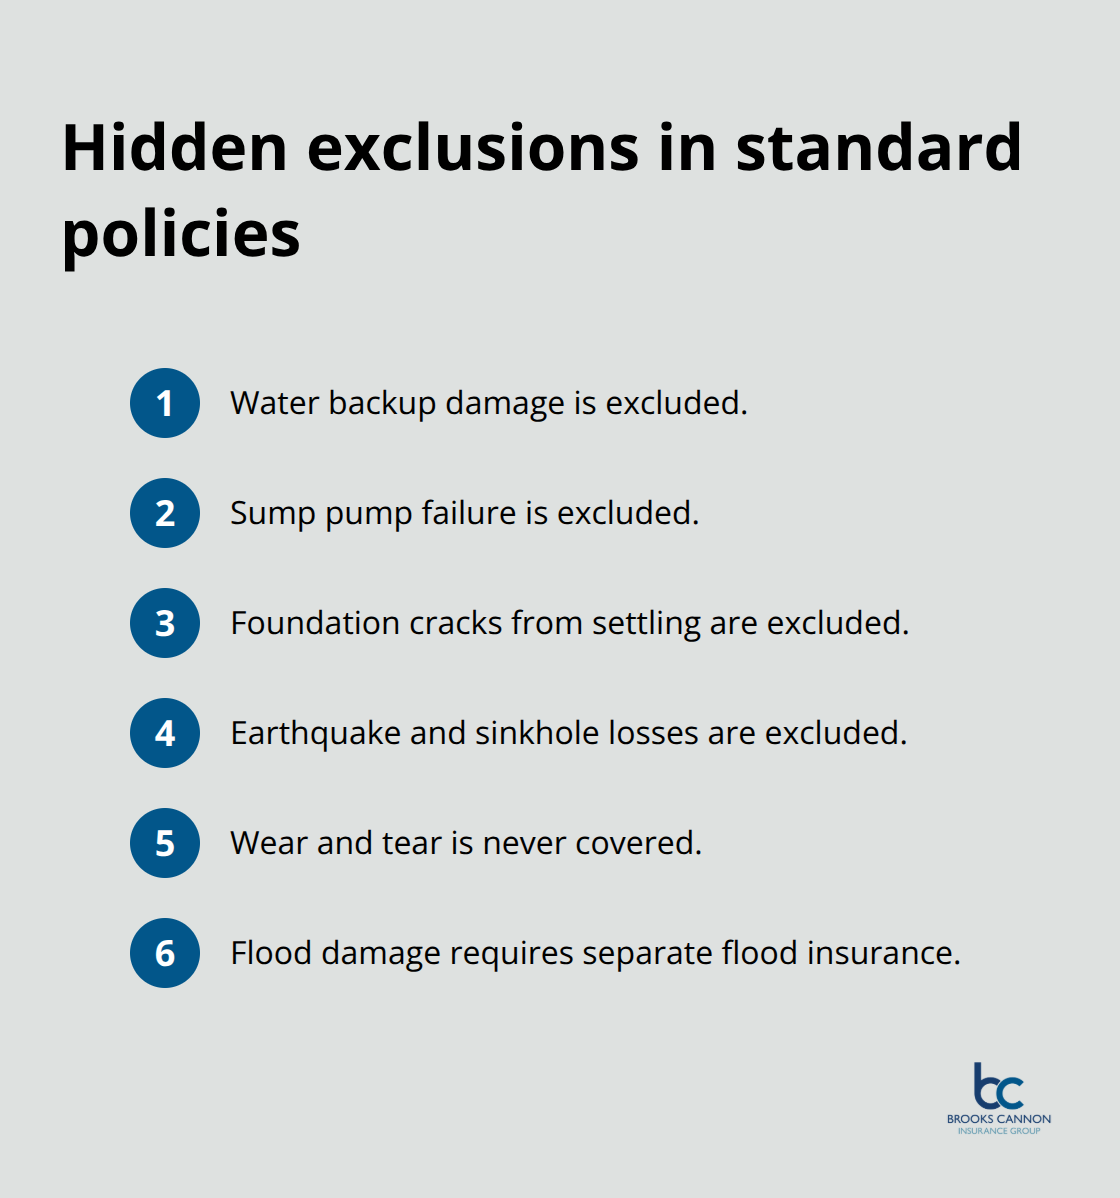
Texas-specific risks create additional gaps. Flood damage isn’t covered under any standard homeowners policy-you need separate flood insurance, and according to the National Flood Insurance Program, many Dallas homeowners skip this coverage when they shouldn’t.
Collections and Valuable Items Face Strict Limits
Collections like fine art, jewelry, and antiques face strict limits under standard coverage, usually capped at $1,500 to $2,500 total for all jewelry combined. If your home contains valuable items worth $50,000 or more, standard coverage leaves you significantly exposed. We’ve worked with clients who discovered after a loss that their $300,000 art collection had only $2,500 in coverage. Wind and hail damage also has limits in many policies, particularly in areas near the coast.
The Real Cost of Coverage Gaps
The gap between what you think you’re covered for and what you actually are covered for is where real financial damage happens. A homeowner in the Dallas area experienced a water backup that flooded their basement, destroying $80,000 worth of stored items-their policy paid nothing because water backup wasn’t included. Another client’s custom jewelry valued at $45,000 was stolen; the policy paid $2,000. These aren’t edge cases; we see this regularly.
Exclusions exist because insurers must manage risk, but your job is to close those gaps with additional endorsements and policies designed specifically for high-value homes. The cost of adding coverage is minimal compared to absorbing a loss yourself. Understanding your specific exclusions now prevents devastating losses later, which is why the next section shows you exactly how to fill these protection gaps.
What Exclusions Actually Cost You
Water Damage Hits Your Wallet Hard
A homeowner with a $2.5 million residence experienced water damage from a burst pipe in their second-floor bathroom, causing $120,000 in damage to hardwood floors, custom cabinetry, and personal property below. Their standard policy covered the structural damage but excluded water damage from internal plumbing failures-they paid $45,000 out of pocket. Another client’s $75,000 wine collection suffered damage when their basement flooded during heavy rains; their policy paid nothing because flood damage carries a blanket exclusion. The Insurance Information Institute reports that water damage and freezing represent a significant portion of homeowners insurance claims, yet many Dallas homeowners carry policies with significant water-related exclusions. The financial gap between expected coverage and actual coverage ranges from thousands to hundreds of thousands of dollars depending on what your specific policy excludes.
Your Assumptions About Coverage Fall Apart Fast
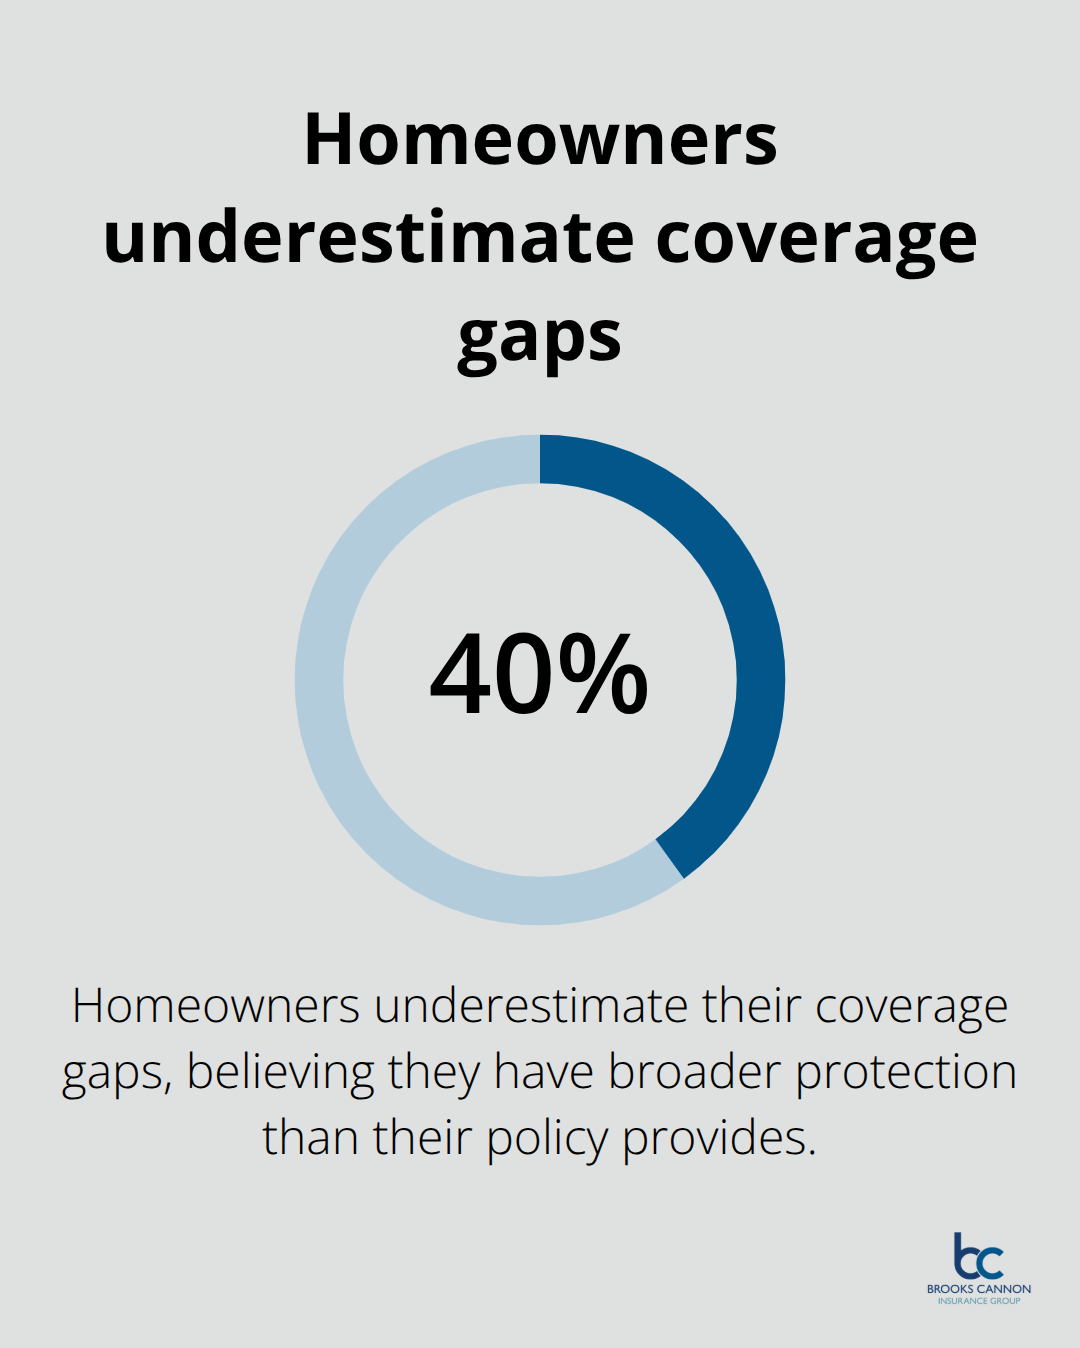
Most Dallas homeowners assume their policy covers damage from common household incidents, but standard policies specifically exclude water backup from sewers or drains, sump pump failures, foundation cracks from settling, and damage from lack of maintenance. A homeowner in the Preston Hollow area discovered their $35,000 in stored collectibles received only $2,500 in coverage after a theft because standard policies cap coverage on jewelry, fine art, and collectibles at those minimal amounts. Another client’s custom home theater system valued at $50,000 suffered damage from an electrical fire; coverage limits on electronics and entertainment equipment left them responsible for $30,000 of the replacement cost. Wind and hail damage carry separate deductibles and sublimits in many policies, particularly in North Texas where hail damage strikes frequently. According to the National Association of Insurance Commissioners, the average homeowner underestimates their coverage gaps by 40%, believing they have broader protection than their actual policy provides.
Close Your Coverage Gaps Before Disaster Strikes
The time to understand your exclusions is now, not after damage occurs. Review your declarations page-the summary section listing coverage amounts and exclusions-with a licensed agent who can identify specific gaps in your protection. For high-value homes in Dallas, this typically means adding scheduled personal property endorsements for art, jewelry, and collectibles, securing separate water backup coverage, and confirming your flood insurance is adequate if you’re in a flood-prone area. The cost of adding these protections typically ranges from $500 to $2,000 annually depending on your home’s value and location, which is minimal compared to absorbing a $50,000 to $100,000 loss yourself. Texas homeowners also benefit from understanding that your homeowners policy and flood insurance operate separately-FEMA’s National Flood Insurance Program data shows that over 20% of flood claims come from properties outside high-risk flood zones, meaning many Dallas homeowners underestimate their flood risk and skip this coverage entirely. The next section shows you exactly which additional endorsements and policies work best for high-value homes in our area.
How to Protect What You Actually Own
Scheduled Personal Property Endorsements for High-Value Items
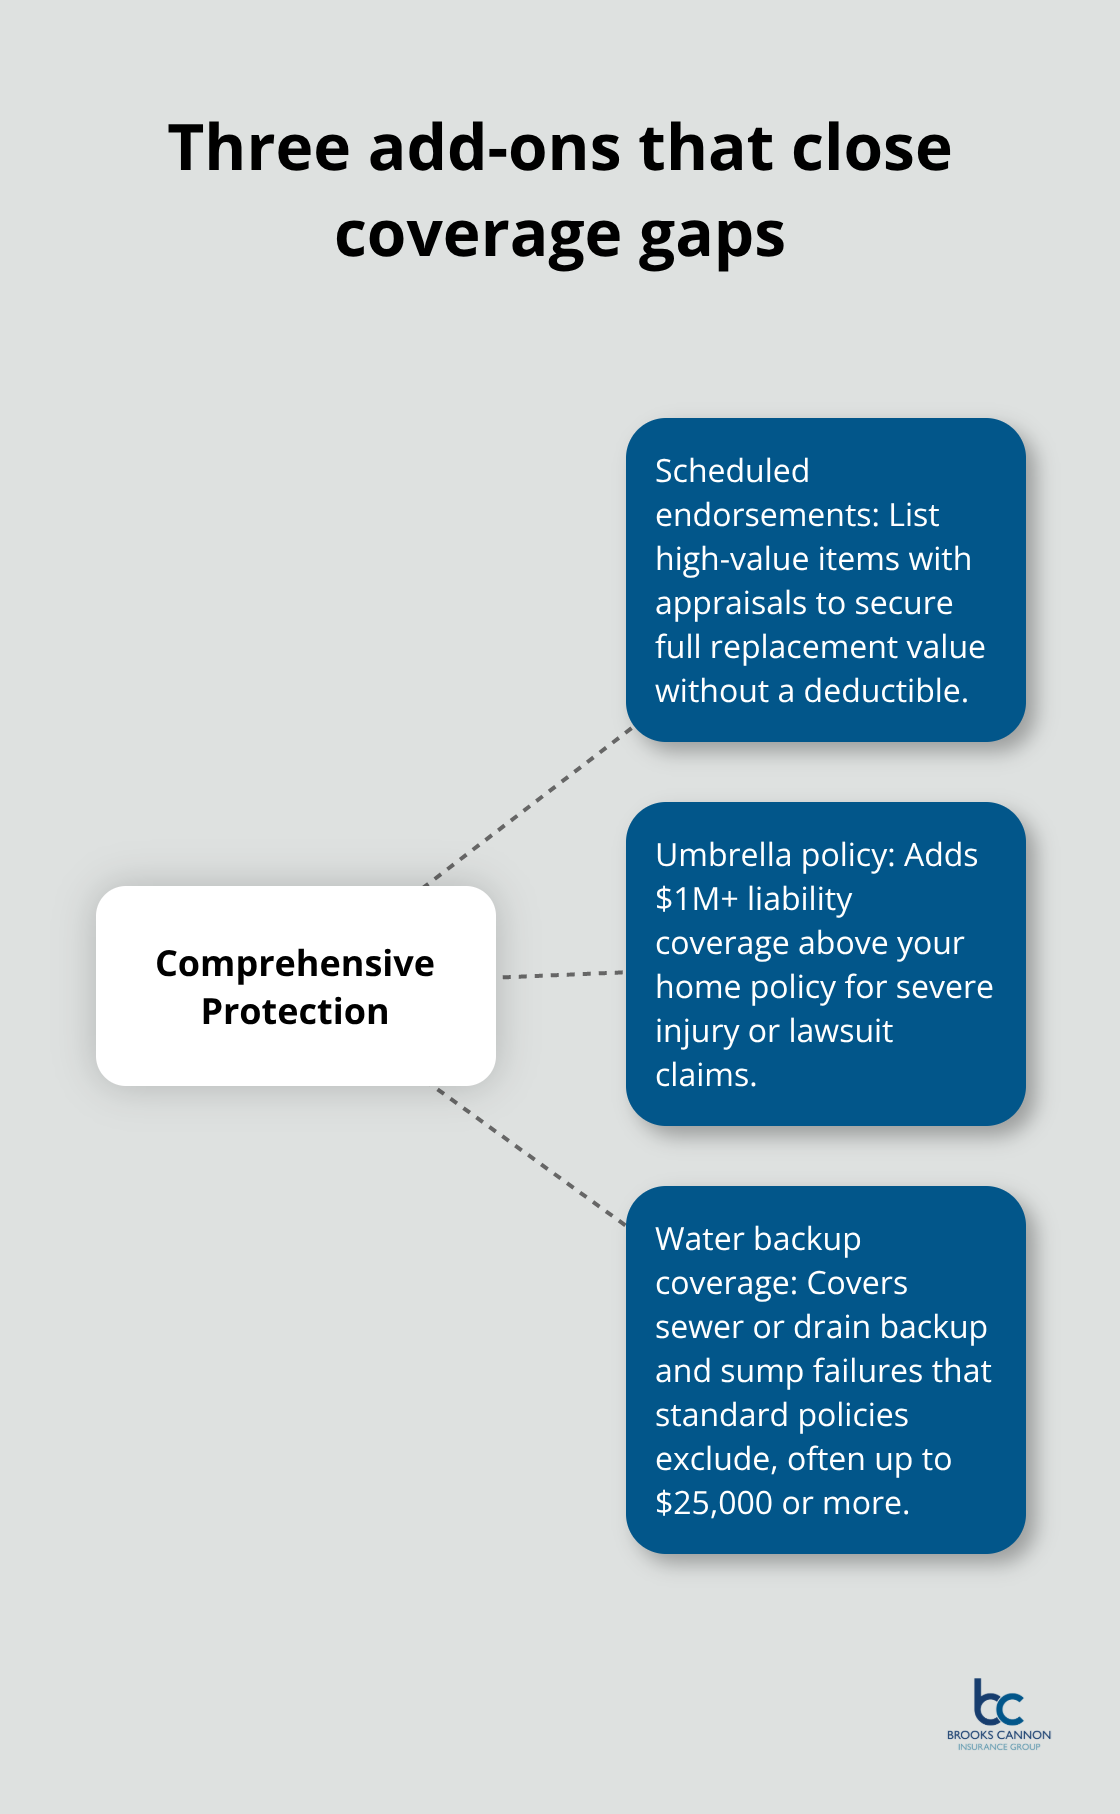
Scheduled personal property endorsements offer the most direct solution for high-value items that exceed standard policy limits. Instead of accepting a $2,500 cap on jewelry, you list specific pieces with their appraised values, and the endorsement covers them at full replacement cost without deductibles. A Dallas homeowner with a $120,000 engagement ring and watch collection pays roughly $300 to $400 annually for scheduled coverage that protects each piece individually. You’ll need professional appraisals from certified gemologists or art valuators, which typically cost $150 to $500 per item but are essential for claim documentation. The endorsement covers theft, loss, and damage worldwide, meaning your jewelry stays protected whether it’s stolen at home or while traveling.
For art collections, vintage wine, rare books, or high-end electronics, scheduled endorsements work the same way. You document each item with photos and appraisals, then add them to your policy. This approach eliminates the frustration of discovering after a loss that your $300,000 art collection had only $2,500 in coverage.
Umbrella Policies for Liability Protection
Umbrella policies provide the second layer of protection, but not for your belongings-they cover liability claims that exceed your homeowners policy limits. A Dallas homeowner with a $2 million residence typically carries a $1 million umbrella policy, which costs between $200 and $400 annually and covers situations where someone is injured on your property and sues for damages beyond your standard liability limit. If a guest falls and requires $500,000 in medical care and decides to sue, your standard homeowners policy covers up to $300,000, and your umbrella policy covers the remaining $200,000. Texas has no cap on liability damages, making umbrella coverage essential for high-net-worth homeowners who have significant assets to protect.
Water Backup Coverage for North Texas Flooding
Water backup coverage is equally critical in North Texas where heavy rains frequently cause basement flooding and sump pump failures. Standard homeowners policies exclude water backup from sewers, storm drains, and sump pump failures-the three most common water-related claims in Dallas. Adding water backup coverage costs $150 to $300 annually and covers damage up to $25,000 or higher depending on your endorsement level. Without this coverage, a $50,000 basement flooding event leaves you responsible for the entire loss.
Combining Protections Into Comprehensive Coverage
These three protections-scheduled endorsements for valuables, umbrella policies for liability, and water backup coverage for flooding-work together to close the gaps that standard policies create. The combination transforms incomplete coverage into comprehensive protection that matches your home’s value. Your licensed insurance agent can review your specific situation and recommend which endorsements make sense for your Dallas property.
Final Thoughts
Your high-value home requires more than a standard policy. High-net-worth exclusions exist in nearly every policy, and ignoring them costs Dallas homeowners tens of thousands of dollars annually. Pull out your declarations page today and read it carefully, looking specifically for water damage exclusions, personal property limits, and flood coverage gaps.
Schedule a conversation with a licensed insurance agent who understands high-value homes in the Dallas area. This isn’t about accepting whatever coverage you currently have-it’s about identifying the specific gaps in your protection and fixing them with targeted endorsements and additional policies. Scheduled personal property coverage for valuables, umbrella policies for liability protection, and water backup endorsements for North Texas flooding address most situations, though your home’s unique characteristics and location may require different protections.
The cost of closing these gaps runs between $500 and $2,000 annually, which protects assets worth millions of dollars. At Brooks Cannon Insurance Group, our team works with multiple top-rated carriers to build customized coverage that matches your home’s actual value and your specific risks. Contact us today to stop accepting incomplete protection.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation